
Local Insurance Agency Utah: Find a Trusted Advisor
Finding the right insurance protection in Utah requires more than just a quick online quote. A local insurance agency Utah can provide personalized guidance that national companies simply can’t match.
At Archibald Insurance Agency, we understand that Utah residents face unique risks-from winter weather damage to liability concerns specific to our state. Working with a trusted local advisor means getting coverage tailored to your actual needs, not a one-size-fits-all policy.
Why Local Agencies Beat National Competitors in Utah
Utah’s Climate Creates Unique Coverage Needs
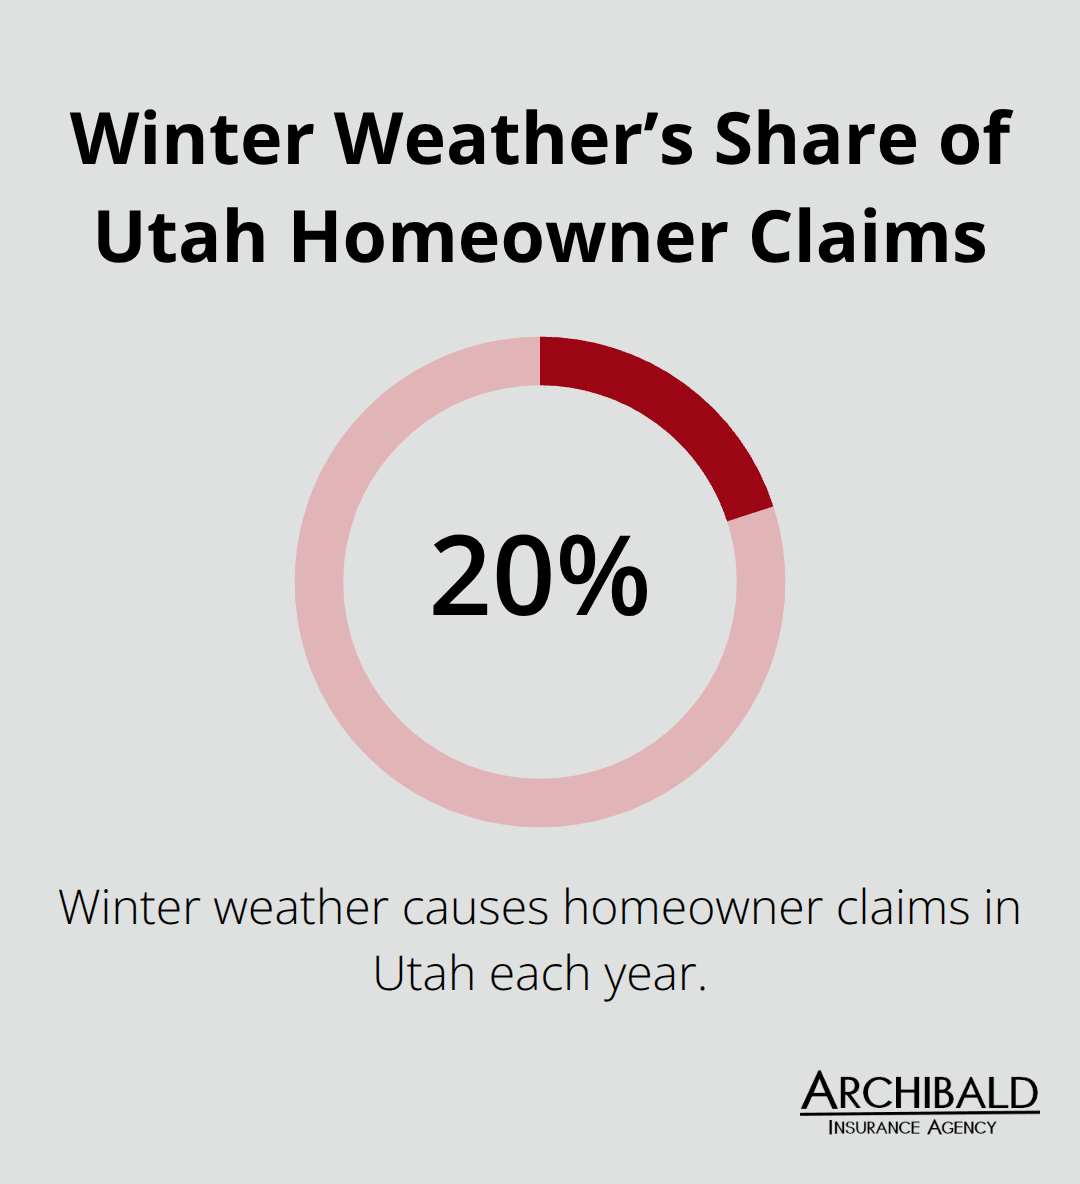
Utah’s insurance landscape demands local expertise that national companies cannot provide. Winter weather causes an estimated 20% of homeowner claims in Utah annually, yet most online insurers offer generic coverage that leaves gaps specific to our climate. A local agency understands that Salt Lake City’s elevation, seasonal temperature swings, and snow load requirements demand different protection than policies written for Florida or Arizona.
Local adjusters maintain relationships with property owners and understand Utah’s specific conditions in ways distant call centers never will. When you need coverage for a downtown Salt Lake City townhome versus a Park City mountain property, the risk profiles are completely different, and a local advisor catches those distinctions before problems occur.
Access to Multiple Carriers Delivers Real Savings
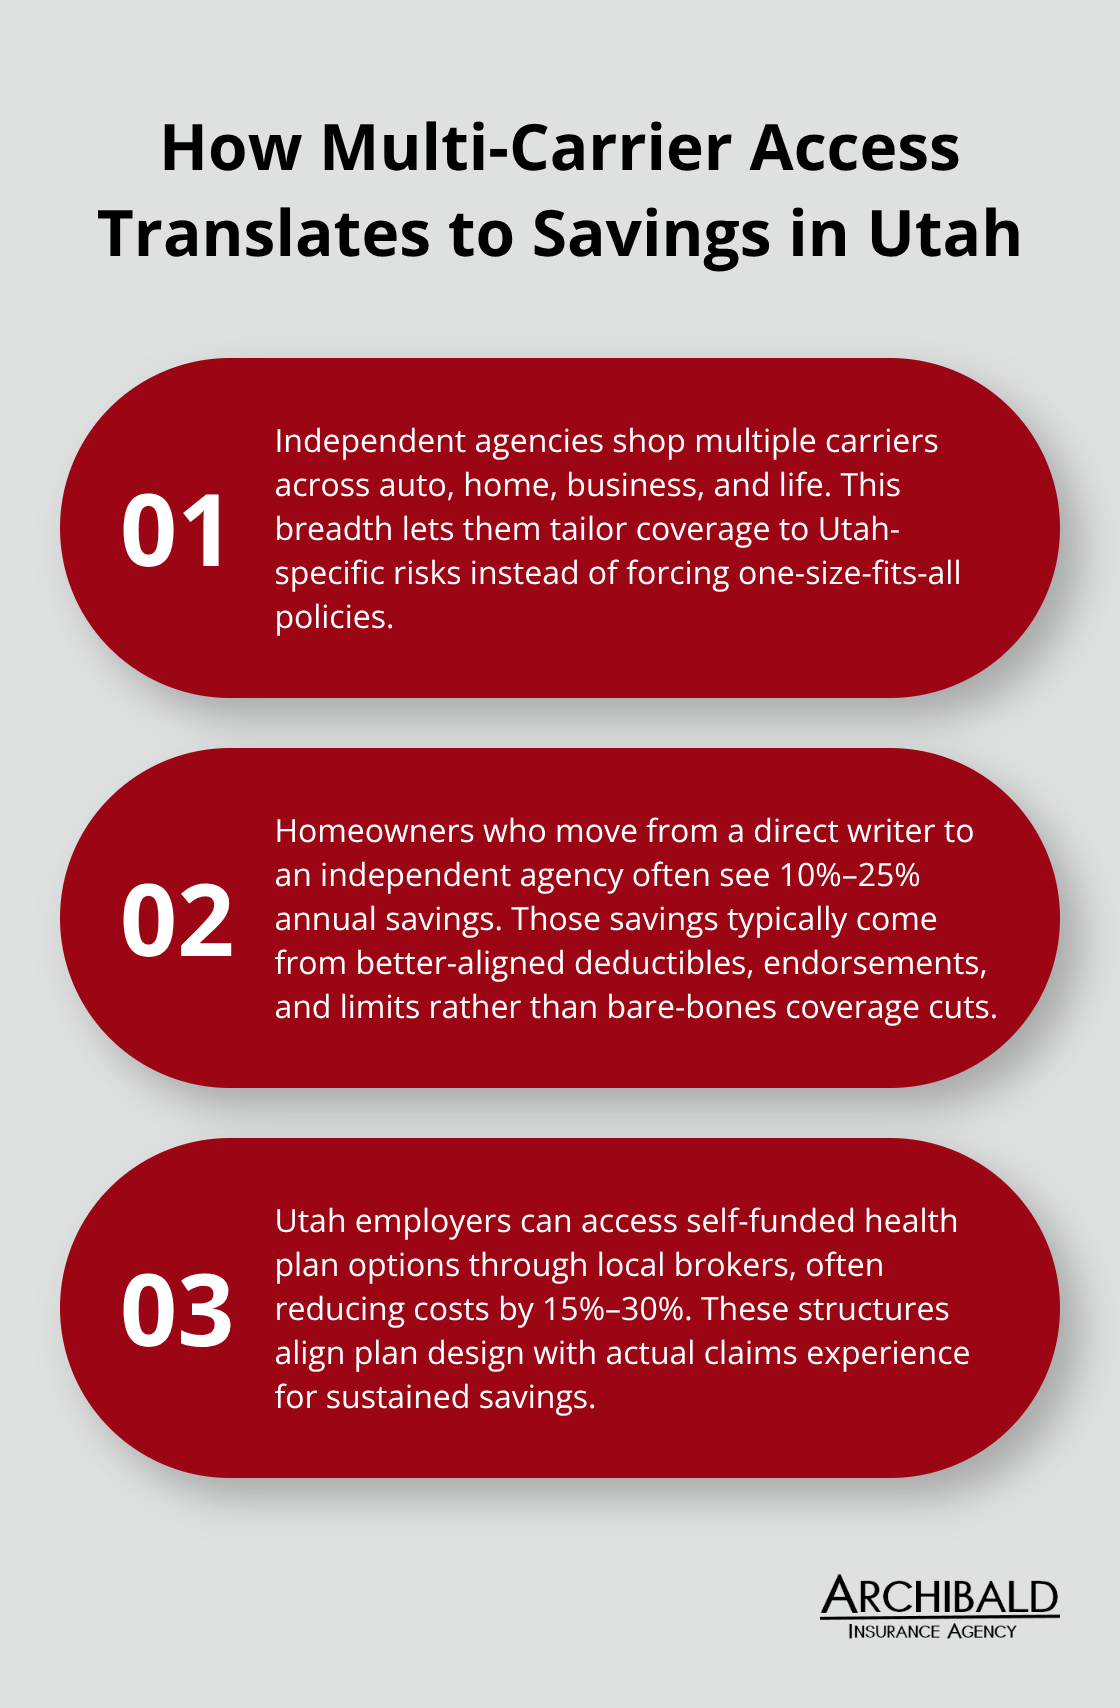
Access to multiple carriers is where independent agencies provide measurable value that captive agents cannot match. The average Utah consumer shopping online sees quotes from two or three insurers, but independent agencies access multiple carriers for auto insurance alone, plus specialized underwriters for business and life coverage. This matters financially: a homeowner switching from a direct writer to an independent agency typically finds 10% to 25% in annual savings through better-matched coverage. Larger employers in Utah benefit even more; self-funded health plan options available through local brokers can reduce costs by 15% to 30% compared to fully insured plans, according to benefits consultants serving Utah companies.
Community Trust Builds Through Local Accountability
Community trust develops differently in Utah than elsewhere. Long-standing local agencies like Beehive Insurance (operating since 1961) have built credibility through decades of consistent service in our market. When your neighbor recommends their insurance agent, that recommendation carries weight because they know how that agency handled their claim after a summer hailstorm or a business liability incident. This local accountability matters more than national brand recognition when you face an actual loss. The next step involves understanding how to identify which local agency truly matches your specific needs and risk profile.
Selecting a Local Agency That Actually Serves Your Needs
Verify Licensing Before You Commit
Start with verification, not reputation. Utah’s Division of Insurance Licensee Search tool lets you confirm that any agent or broker you’re considering holds active licenses for the specific products you need-auto, home, business, or life coverage. This step matters more than you’d think. A broker might excel at employee benefits but lack proper licensing for commercial property coverage, forcing you to work with multiple advisors instead of one trusted source. When you contact potential agencies, ask directly about their licenses and their access to carriers in your specific insurance category. Independent agencies can access multiple carriers across auto, home, business, and life products, which means one call handles your entire portfolio instead of juggling separate relationships.
Compare Quotes Side-by-Side for Real Savings
Pricing comparison requires seeing actual quotes side-by-side, not just asking for estimates over the phone. Request quotes from at least three local agencies for identical coverage levels-same deductibles, same liability limits, same riders or endorsements. This prevents the trap of comparing different products at different price points.
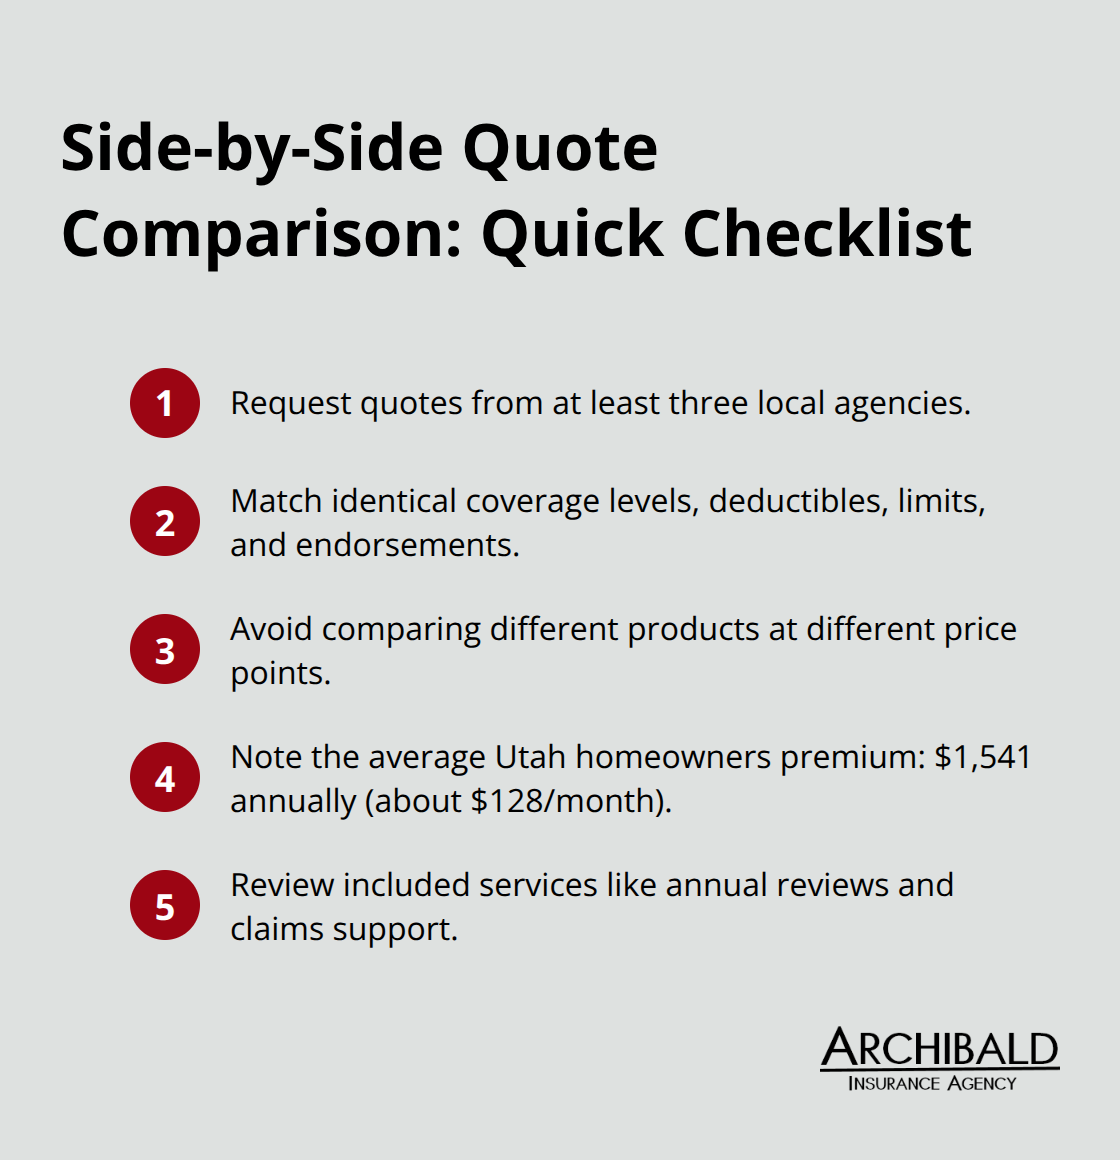
The average cost of a homeowners policy in Utah is $1,541 annually or about $128 per month, according to the National Association of Realtors. More importantly, compare what each agency includes in their service package. Some agencies offer annual policy reviews, claims support, or business continuity planning at no extra cost, while others charge separately for these services.
Evaluate Service Quality and Responsiveness
Ask whether the agency provides a dedicated agent or rotates you through different staff members-continuity matters when you file a claim and need someone who already knows your situation. Responsiveness shows up immediately: if an agency takes more than 24 hours to return your call or email, that’s your answer about how they’ll treat you after you’ve paid your premium. Test their responsiveness by calling with a specific question and timing how long they take to respond. Real local agencies maintain enough staff to answer calls during business hours, not just callbacks the next day. The quality of service you receive before you purchase coverage directly predicts the quality you’ll experience when you actually need to file a claim.
What Insurance Coverage Are Utah Residents Actually Missing
Homeowners Underestimate Replacement Costs
Utah homeowners commonly carry limits that made sense five or ten years ago but fall short of actual replacement costs today. A home that cost $350,000 to purchase might require $450,000 to fully rebuild after a total loss, yet many policies cap coverage at the original purchase price. Winter storms, hail damage, and foundation issues from Utah’s freeze-thaw cycles drive claim costs higher than homeowners anticipate. When you receive a homeowners policy quote, your agent should walk you through the replacement cost calculation, not just the dwelling limit. If your agent skips this conversation or quotes limits based on your mortgage balance rather than actual replacement costs, that’s a red flag worth addressing with a different agency.
Business Liability Limits Fall Short of Actual Exposure
Utah business owners face steep gaps in liability protection. A single lawsuit from a customer injury, property damage, or professional error can exceed a typical general liability policy’s limits within hours. Construction companies, contractors, and service businesses operating in Utah frequently carry $1 million in general liability coverage when their actual exposure justifies $2 million or higher, especially if they work on larger commercial projects or residential developments. The cost difference between these limits often amounts to just $30 to $50 monthly, yet most businesses never ask their agent whether their limits match their actual risk profile.
Life Insurance Represents the Most Common Blind Spot
Life insurance represents the most common blind spot across Utah families. Parents with young children frequently carry no life insurance or amounts insufficient to replace their income and cover final expenses. A working parent earning $60,000 annually should try carrying $500,000 to $750,000 in term life coverage, yet many Utah families either skip this protection entirely or purchase $100,000 policies that sound adequate until a spouse dies and the surviving family faces immediate financial crisis. Term life insurance costs roughly $25 to $40 monthly for a healthy 40-year-old seeking $500,000 in coverage, making this protection genuinely affordable for most households.
Ask the Hard Questions About Your Coverage
Work with a local advisor and ask directly whether your current coverage would actually pay your bills if you died today, your home burned, or you faced a major liability claim. That conversation forces the numbers into focus and prevents the regret that follows underinsurance. Your agent should explain exactly what each policy covers and what gaps exist in your protection. This direct assessment reveals whether your current policies match your actual financial obligations and family needs.
Final Thoughts
A local insurance agency Utah provides protection that matches your actual life, not a generic template designed for national markets. We at Archibald Insurance Agency have seen firsthand how personalized guidance prevents the costly gaps that leave families and businesses exposed. When your agent understands Utah’s climate risks, knows the local business landscape, and maintains relationships with multiple carriers, your coverage reflects reality instead of assumptions.
Contact Archibald Insurance Agency and discuss your specific situation: your home’s replacement cost, your business liability exposure, your family’s income protection needs. Request quotes from multiple agencies using identical coverage specifications so you can compare actual pricing and service quality. Verify licensing through Utah’s Division of Insurance, then evaluate responsiveness by timing how quickly each agency returns your calls and emails.
Reach out to a trusted local advisor and have the conversation about whether your current coverage actually protects what matters most. That conversation takes an hour and could save your family or business from financial devastation. You deserve an advisor who knows your community and your risks, not a distant call center or an algorithm.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation


