Rideshare Insurance Utah: What Drivers Should Know
Rideshare driving in Utah offers flexibility and income, but it exposes you to serious liability gaps that standard auto insurance won’t cover. Your personal policy stops working the moment you accept a ride request, leaving you financially vulnerable during some of your most active driving hours.
We at Archibald Insurance Agency help rideshare drivers in Utah close these dangerous coverage gaps with policies designed specifically for your work. This guide walks you through the three coverage periods, what protection you actually need, and how to pick the right plan for your situation.
What Utah Law Actually Requires for Rideshare Drivers
The Coverage Phases That Define Your Protection
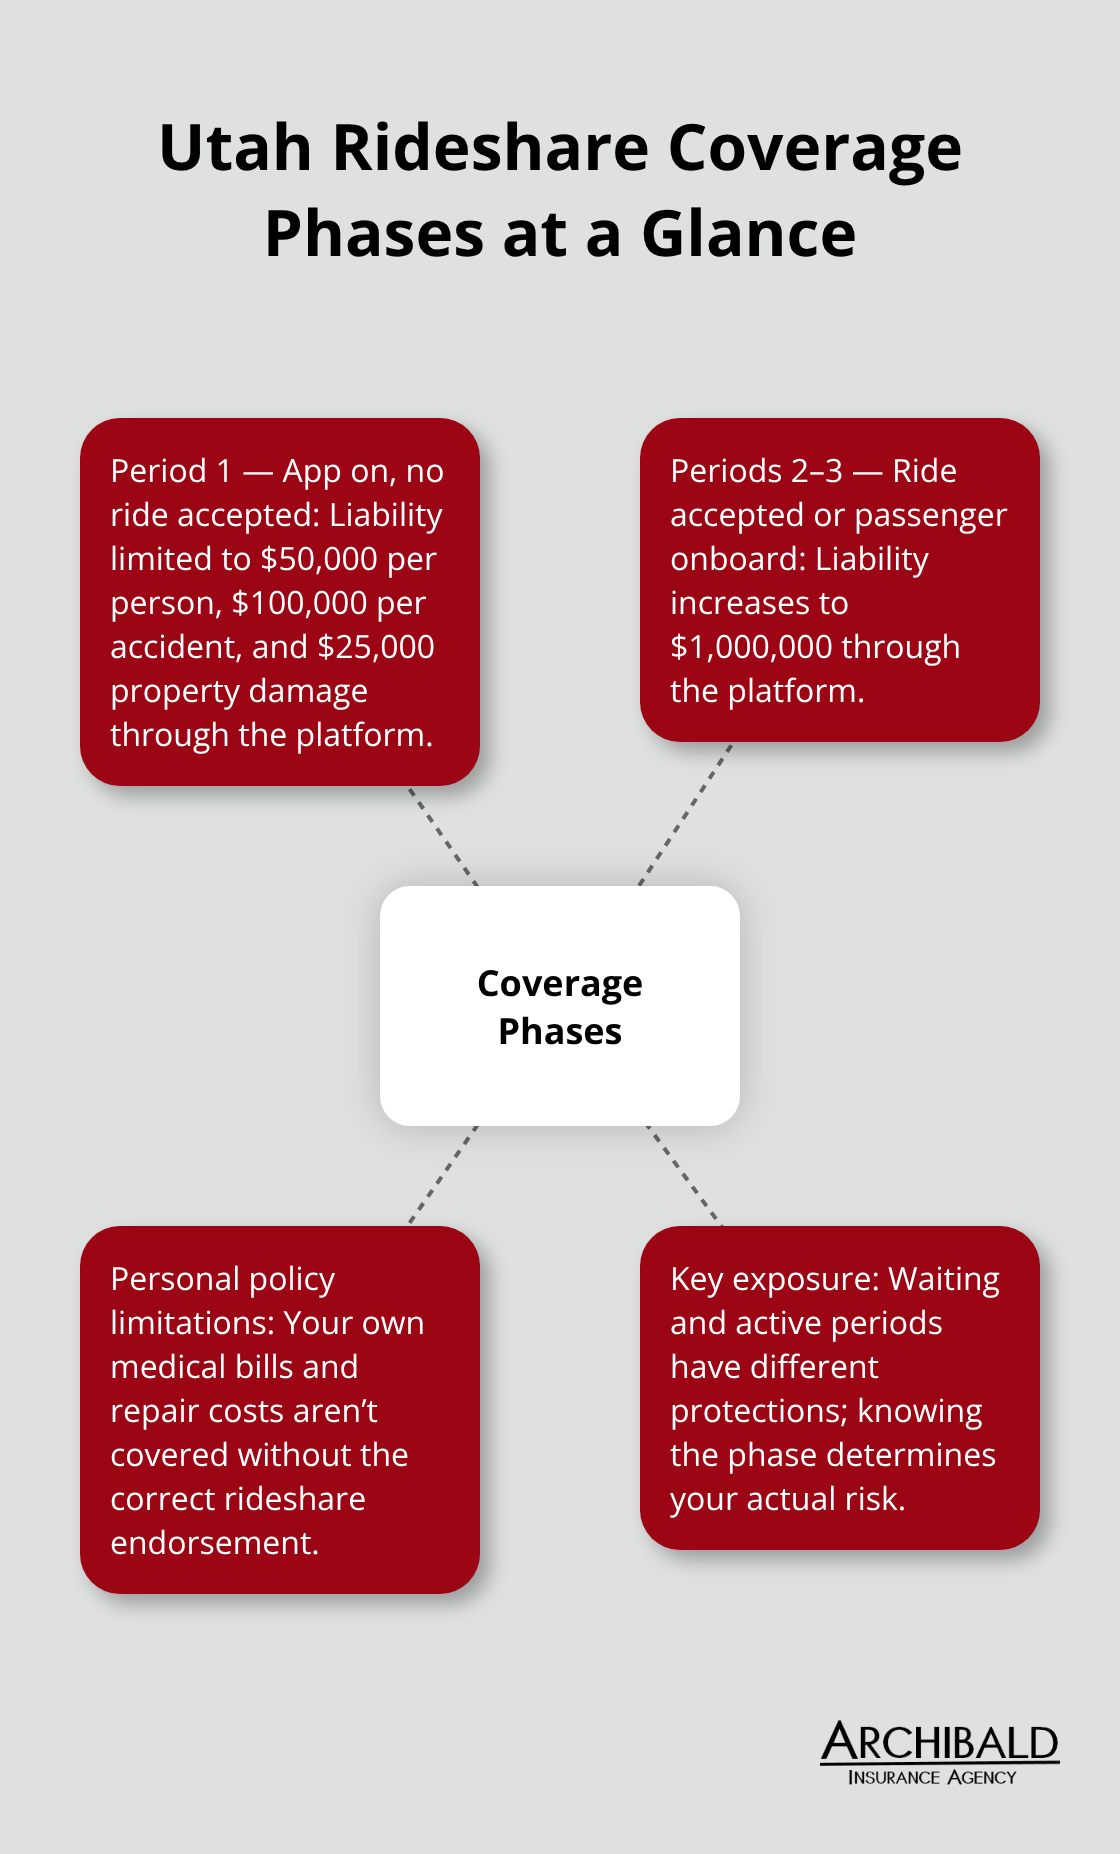
Utah mandates that rideshare drivers carry insurance while actively engaged in rideshare work, but your personal auto policy stops covering you the moment you log into Uber or Lyft. State law recognizes this gap by allowing transportation network companies to provide limited liability coverage during specific periods of your shift, but those periods come with strict limitations that create real exposure. The framework breaks down into distinct phases: when your app is on but you haven’t accepted a ride yet, coverage drops to $50,000 per person and $100,000 per accident in liability through the platform, with just $25,000 for property damage. Once you accept a ride or have a passenger in your vehicle, coverage jumps to $1 million, but this doesn’t protect your own medical bills or repair costs unless you have the right endorsement on your personal policy.
Why Your Personal Policy Won’t Help
Most drivers don’t realize that their personal insurance excludes rideshare, meaning you face a complete coverage denial if an accident happens during those waiting periods between accepting rides. Your personal policy stops working the instant you log in, and the platform’s limited liability coverage ($50,000 per person during waiting periods) leaves you massively underprotected. This gap exists because insurers classify rideshare as commercial activity, which falls outside standard personal auto coverage. The waiting phase-the period between accepting a ride request and starting the trip-often leaves you with no protection at all.
The Real Cost of Rideshare Endorsements
Utah insurers offering rideshare endorsements typically charge $150–$400 per year, yet many drivers skip this protection to save money and end up completely uncovered when they need it most. Progressive, Safeco, Auto-Owners Insurance, and United Insurance Group all offer state-compliant rideshare options in Utah, and local independent agents can help you compare what each covers. Your deductible becomes critical here: while the platform provides $1 million in liability coverage during active rides, many policies carry deductibles as high as $2,500, meaning you pay that amount out of pocket before coverage kicks in. The difference between your personal policy deductible and the platform’s deductible ($2,500) represents a significant financial exposure that an endorsement can bridge.
What the National Association of Insurance Commissioners Recommends
The National Association of Insurance Commissioners recommends confirming exactly what the platform covers in each phase before you start driving. Most drivers never take this step, which leaves them vulnerable to claim denials when accidents occur. You need to contact your current insurer and ask whether they offer rideshare endorsements and what those endorsements actually cover. If your current carrier doesn’t offer rideshare protection, you’ll need to find one that does or add a commercial auto policy to your existing coverage.
Finding the Right Coverage for Your Situation
Your actual driving pattern determines what coverage you truly need. If you drive full-time for rideshare, a simple endorsement may not provide enough protection, and you might need a commercial auto policy instead. Part-time drivers often find that a rideshare endorsement fills the gaps in their personal policy without the higher cost of full commercial coverage. The key is matching your coverage to how you actually drive-not to what the platform tells you is sufficient. Your next step involves reviewing your current policy language and contacting insurers to understand exactly what protection you can add before your next shift.
Coverage During Each Phase of Your Shift
The three-period framework that governs rideshare insurance in Utah creates dramatically different protection levels depending on whether you wait for a ride, actively transport a passenger, or work between fares. Understanding what each period covers-and what it doesn’t-determines whether you face financial ruin or solid protection after an accident.
Period 1: The Waiting Phase Gap
Period 1 coverage applies when your app is on but you have not accepted a ride. During this waiting phase, Uber and Lyft provide only $50,000 per person in liability coverage, $100,000 per accident, and a mere $25,000 for property damage. This protection is so thin that a single serious injury claim exceeds it instantly. Your personal auto policy will not help because it excludes commercial rideshare activity, leaving you personally liable for anything beyond the platform’s $50,000 threshold.
A rideshare endorsement fills this exact gap by extending your personal policy’s higher liability limits into Period 1, typically providing $100,000 or more in coverage where the platform leaves you exposed. If you drive during Utah winters when accident risk climbs, this gap becomes genuinely dangerous-one collision during a waiting period could cost you tens of thousands out of pocket. The endorsement transforms Period 1 from a financial liability into manageable risk.
Period 2 and Period 3: The Deductible Problem
Period 2 and Period 3 coverage jumps to $1 million in liability once you accept a ride or have a passenger in your vehicle, which sounds substantial until you factor in deductibles. The platform’s deductible can reach $2,500, meaning you pay that amount before their $1 million kicks in. Your personal rideshare endorsement typically carries a lower deductible ($500–$1,000), so having both policies means you hit the lower deductible first and receive better protection overall.
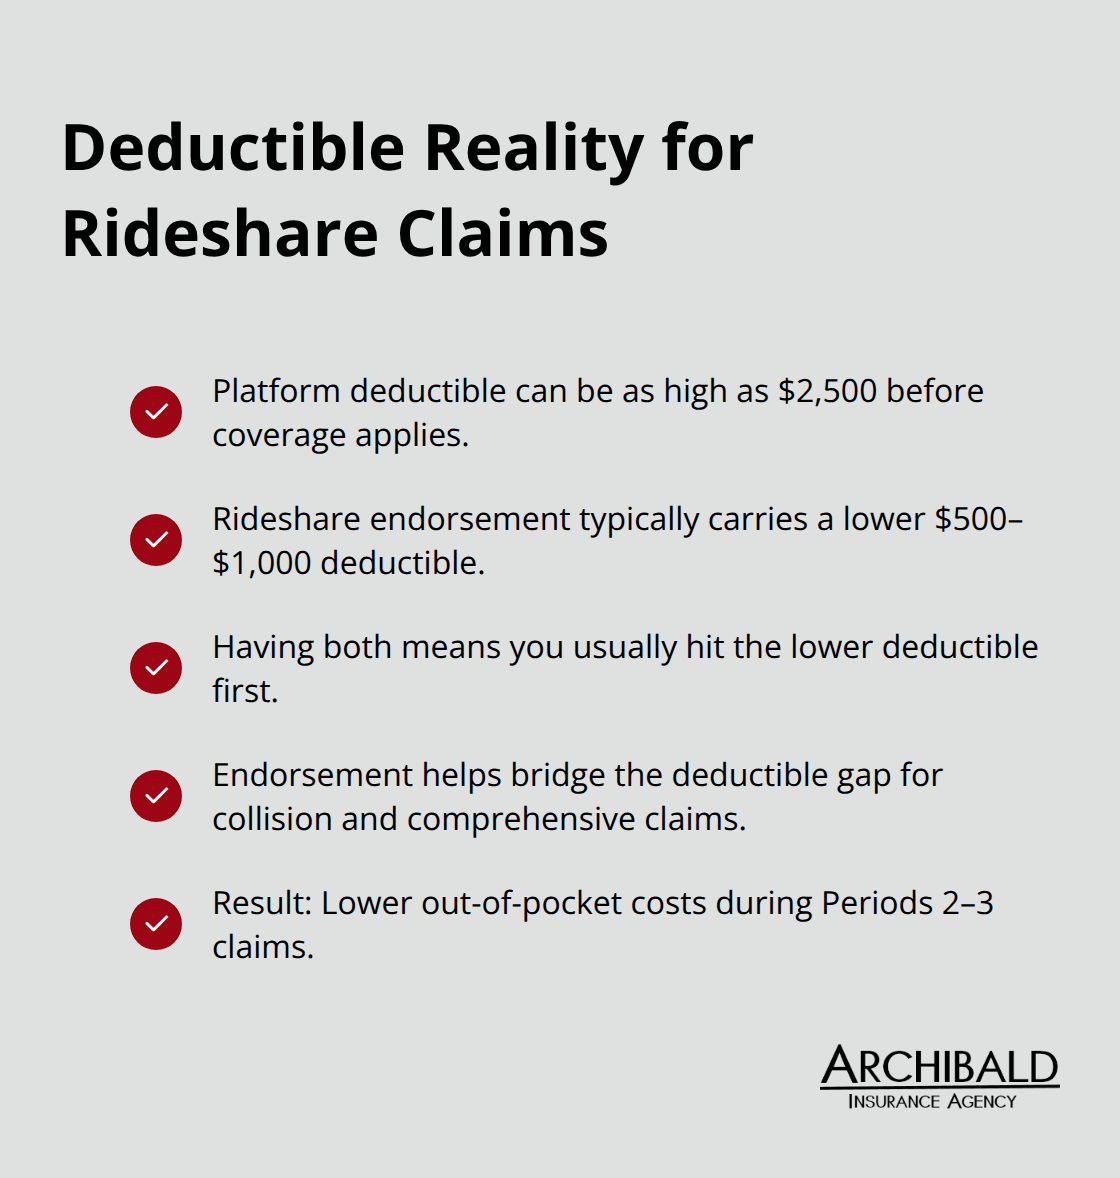
Collision and comprehensive coverage under the platform policy covers vehicle damage, but the high deductible remains your problem. If you hit another car during a pickup, you pay $2,500 out of pocket before the platform’s collision coverage applies. A rideshare endorsement reduces this exposure significantly by bridging the deductible gap and protecting your vehicle when accidents happen.
Uninsured Motorist Protection and Coordination
Uninsured and underinsured motorist coverage is included in the platform’s $1 million protection, which matters if the other driver lacks insurance or carries minimal coverage. This protection shields you if you are hit by an uninsured driver, covering your medical bills and vehicle damage when the at-fault party cannot pay. The practical reality is that Period 2 and Period 3 require you to understand your actual out-of-pocket costs during a claim.
Contact your insurer about exact deductible stacking and how your endorsement coordinates with the platform’s coverage so you know what you will actually pay if an accident occurs. Progressive, Safeco, Auto-Owners Insurance, and United Insurance Group all offer state-compliant rideshare options in Utah, and local independent agents can walk you through how these policies work together. The difference between your personal policy deductible and the platform’s deductible represents significant financial exposure that proper coordination eliminates.
Choosing Coverage That Matches Your Actual Driving
Your actual driving pattern determines what coverage you truly need. If you drive full-time for rideshare, a simple endorsement may not provide enough protection, and you might need a commercial auto policy instead. Part-time drivers often find that a rideshare endorsement fills the gaps in their personal policy without the higher cost of full commercial coverage. The key is matching your coverage to how you actually drive-not to what the platform tells you is sufficient.
Your next step involves reviewing your current policy language and contacting insurers to understand exactly what protection you can add before your next shift. Once you have selected the right coverage for your situation, you will need to understand how to file a claim when accidents occur and what documentation protects your interests during the claims process.
Picking the Right Coverage for Your Driving Reality
Match Your Coverage to Your Actual Mileage
Your rideshare income depends on how much you drive and when you drive, so your insurance choice must match that specific pattern. A driver working 10 hours per week faces completely different risks than someone driving 40 hours weekly, yet many drivers apply generic coverage recommendations instead of analyzing their actual exposure. Track your monthly mileage for one full month while driving for Uber or Lyft, then calculate what percentage of your total driving falls into rideshare work. If rideshare represents less than 25 percent of your annual mileage, a rideshare endorsement costing $150–$400 per year typically delivers solid protection at minimal cost. If you exceed 50 percent rideshare driving, however, a commercial auto policy becomes more cost-effective than stacking endorsements on a personal policy, since commercial policies are designed specifically for drivers who earn income through driving.
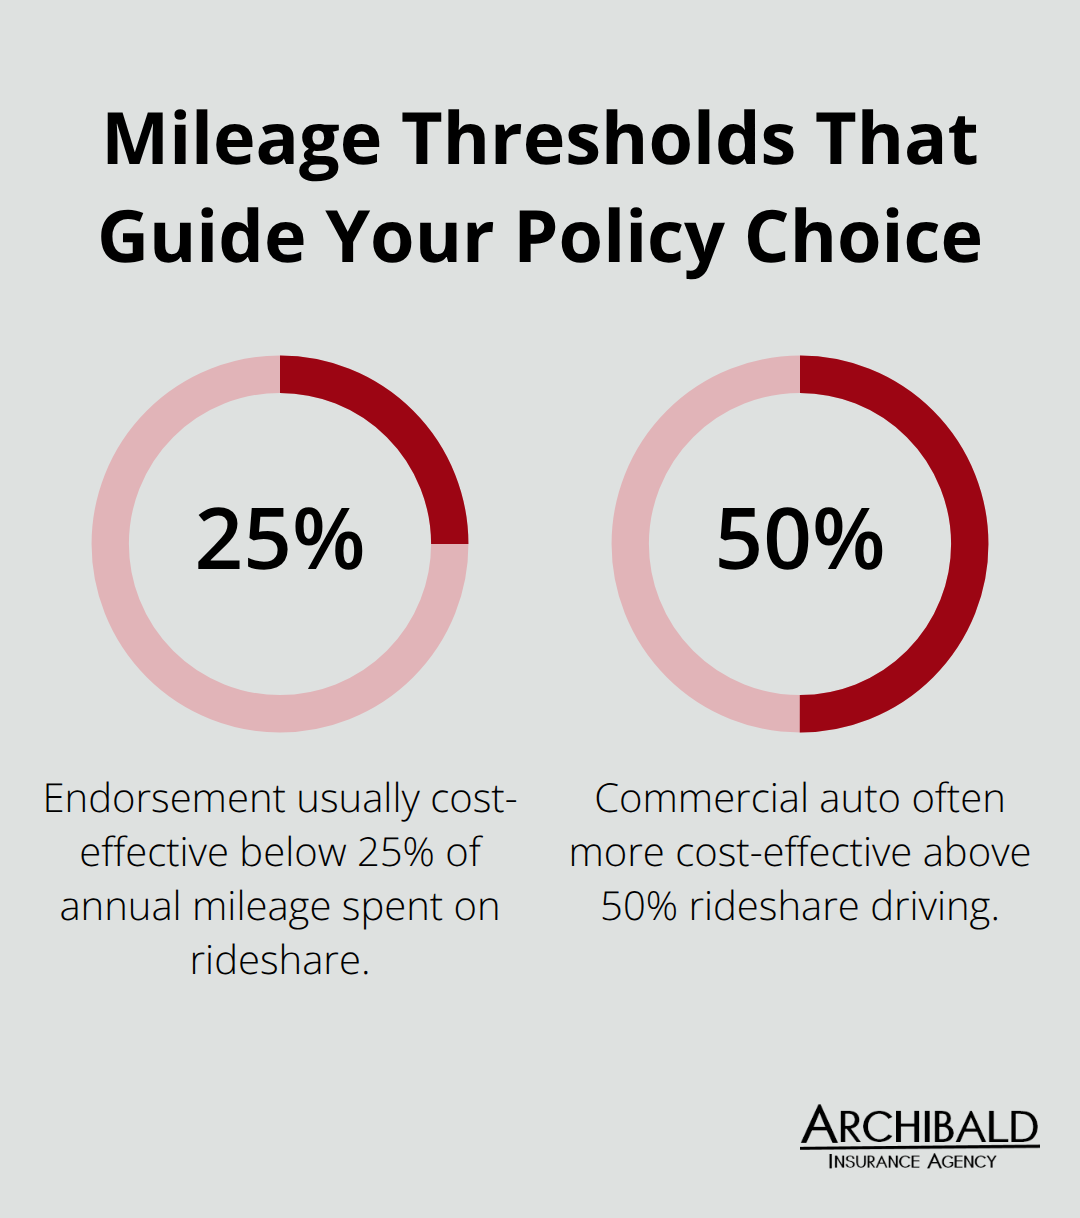
The Insurance Information Institute recommends this frequency-based assessment as the foundation for choosing between endorsement and commercial coverage. Local Utah agents at Progressive, Safeco, Auto-Owners Insurance, and United Insurance Group can calculate which approach saves you money based on your actual driving pattern.
Compare Deductibles Across Policies
Coverage limits and deductibles create the real financial difference between policies, and comparing numbers directly reveals which option protects you best. The platform provides $1 million in liability during active rides but charges a $2,500 deductible, meaning you absorb that amount personally before coverage activates. A rideshare endorsement typically carries a $500–$1,000 deductible instead, dramatically reducing your out-of-pocket exposure during claims. If you drive in Salt Lake City or Park City where traffic density increases accident frequency, the lower deductible becomes genuinely valuable-one accident could cost you an extra $1,500 in out-of-pocket expenses if you rely solely on the platform’s high deductible.
Collision and comprehensive coverage under your endorsement also protects your vehicle’s repair costs with manageable deductibles, whereas the platform’s collision coverage leaves you vulnerable to high upfront costs. Compare specific policy language across carriers rather than shopping by price alone, since a $10 monthly premium difference means nothing if the deductible difference costs you thousands during a claim.
Evaluate Vehicle Protection Options
Your vehicle represents significant financial exposure during rideshare work, and collision and comprehensive coverage determine whether an accident becomes manageable or catastrophic. The platform’s collision coverage applies to your vehicle during active rides, but the $2,500 deductible means you pay that amount out of pocket before repairs begin. A rideshare endorsement reduces this exposure significantly by bridging the deductible gap and protecting your vehicle when accidents occur. If you drive an older vehicle with lower market value, comprehensive coverage becomes less critical, but collision protection remains essential since you operate commercially and face higher accident risk than standard personal drivers.
Progressive, Safeco, Auto-Owners Insurance, and United Insurance Group all offer state-compliant rideshare options in Utah with varying collision and comprehensive limits. Contact multiple carriers to understand exactly what vehicle damage protection each policy provides and what deductible you would pay if an accident occurs.
Final Thoughts
Rideshare insurance in Utah protects your income and your financial future when accidents happen. The three-period framework creates real coverage gaps that your personal auto policy cannot fill, and relying solely on the platform’s limited liability leaves you personally responsible for thousands in damages. A rideshare endorsement costing $150–$400 annually bridges these gaps and reduces your deductible exposure dramatically, transforming Period 1 waiting time from a financial liability into manageable risk.
Your actual driving pattern determines whether an endorsement or commercial auto policy makes sense for your situation. Part-time drivers typically find that a rideshare endorsement delivers solid protection without the higher cost of full commercial coverage, while drivers exceeding 50 percent rideshare work often save money with a dedicated commercial policy. The key is matching your coverage to how you actually drive, not to generic recommendations that ignore your specific mileage and income level.
Contact Archibald Insurance Agency to review your current policy and understand what rideshare insurance Utah protection you actually need. We represent numerous carriers including Progressive, Safeco, Auto-Owners Insurance, and United Insurance Group, giving you access to multiple rideshare options without switching agencies. Our team walks you through deductible coordination, vehicle protection options, and how endorsements work alongside platform coverage to ensure you face no gaps during your next shift.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation
 The trend of utilizing platforms like Airbnb, VRBO, and HomeAway to rent out homes and generate additional income is gaining popularity among homeowners. It’s a fantastic opportunity to save money for college, pay off your mortgage, finance a remodeling project, or simply bolster your savings. However, before diving headfirst into the realm of short-term vacation rentals, it’s important to consider the risks associated with becoming a landlord.