
Auto Insurance Salt Lake: Your Guide to Coverage and Savings
Auto insurance in Salt Lake City doesn’t have to be complicated or expensive. We at Archibald Insurance Agency help Utah drivers find coverage that actually protects them without breaking the bank.
This guide walks you through the coverage types you need, what drives your rates up or down, and concrete ways to cut your costs.
Understanding Auto Insurance Coverage Types in Utah
Utah’s Liability Coverage Requirements
Utah law mandates that every driver carry liability coverage, which pays for injuries and property damage you cause to others. The state’s minimum requirements are 25/65/15, meaning $25,000 for injury per person, $65,000 total per accident, and $15,000 for property damage. However, these minimums are dangerously low. A single accident involving multiple vehicles or serious injuries can easily exceed these limits, leaving you personally liable for thousands of dollars.
We recommend carrying at least 100/300/100 coverage, which costs only slightly more but protects your assets significantly better. If you have meaningful savings or own a home, higher limits make financial sense because a lawsuit judgment can follow you for years.
Collision and Comprehensive Coverage for Your Vehicle
Collision and comprehensive coverage protects your own vehicle rather than others. Collision covers accidents with other vehicles or objects, while comprehensive handles theft, weather, vandalism, and animal strikes. These aren’t required by law if you own your car outright, but your lender will demand them if you’re financing or leasing.
The trade-off involves your deductible, typically $500 or $1,000. A higher deductible lowers your premium but means you pay more out-of-pocket when something happens. For vehicles worth less than $5,000, dropping comprehensive and collision often makes sense financially.
Uninsured and Underinsured Motorist Protection
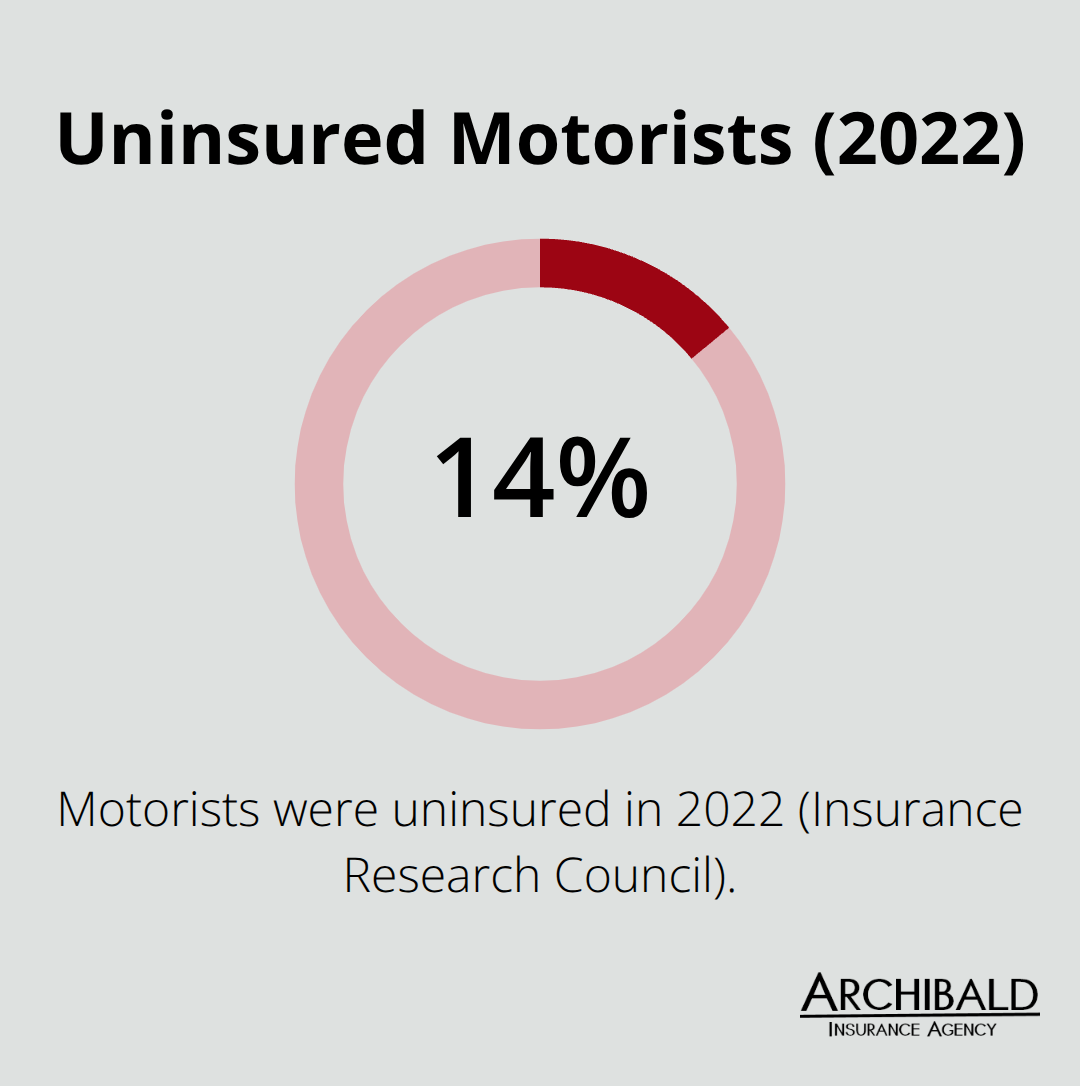
Utah drivers should carry uninsured and underinsured motorist coverage. In 2022, 14.0 percent of motorists were uninsured, according to the Insurance Research Council. This coverage protects you if an uninsured or underinsured driver causes an accident. It’s remarkably affordable and covers your medical bills and vehicle damage when the other driver can’t pay.
Many drivers skip this protection and regret it later when facing medical bills from an uninsured driver’s negligence. Understanding these three coverage pillars positions you to make informed decisions about what protects your finances best. Your next step involves learning what actually drives your rates up or down.
What Drives Your Auto Insurance Rates Up or Down
Your Driving Record Sets the Foundation
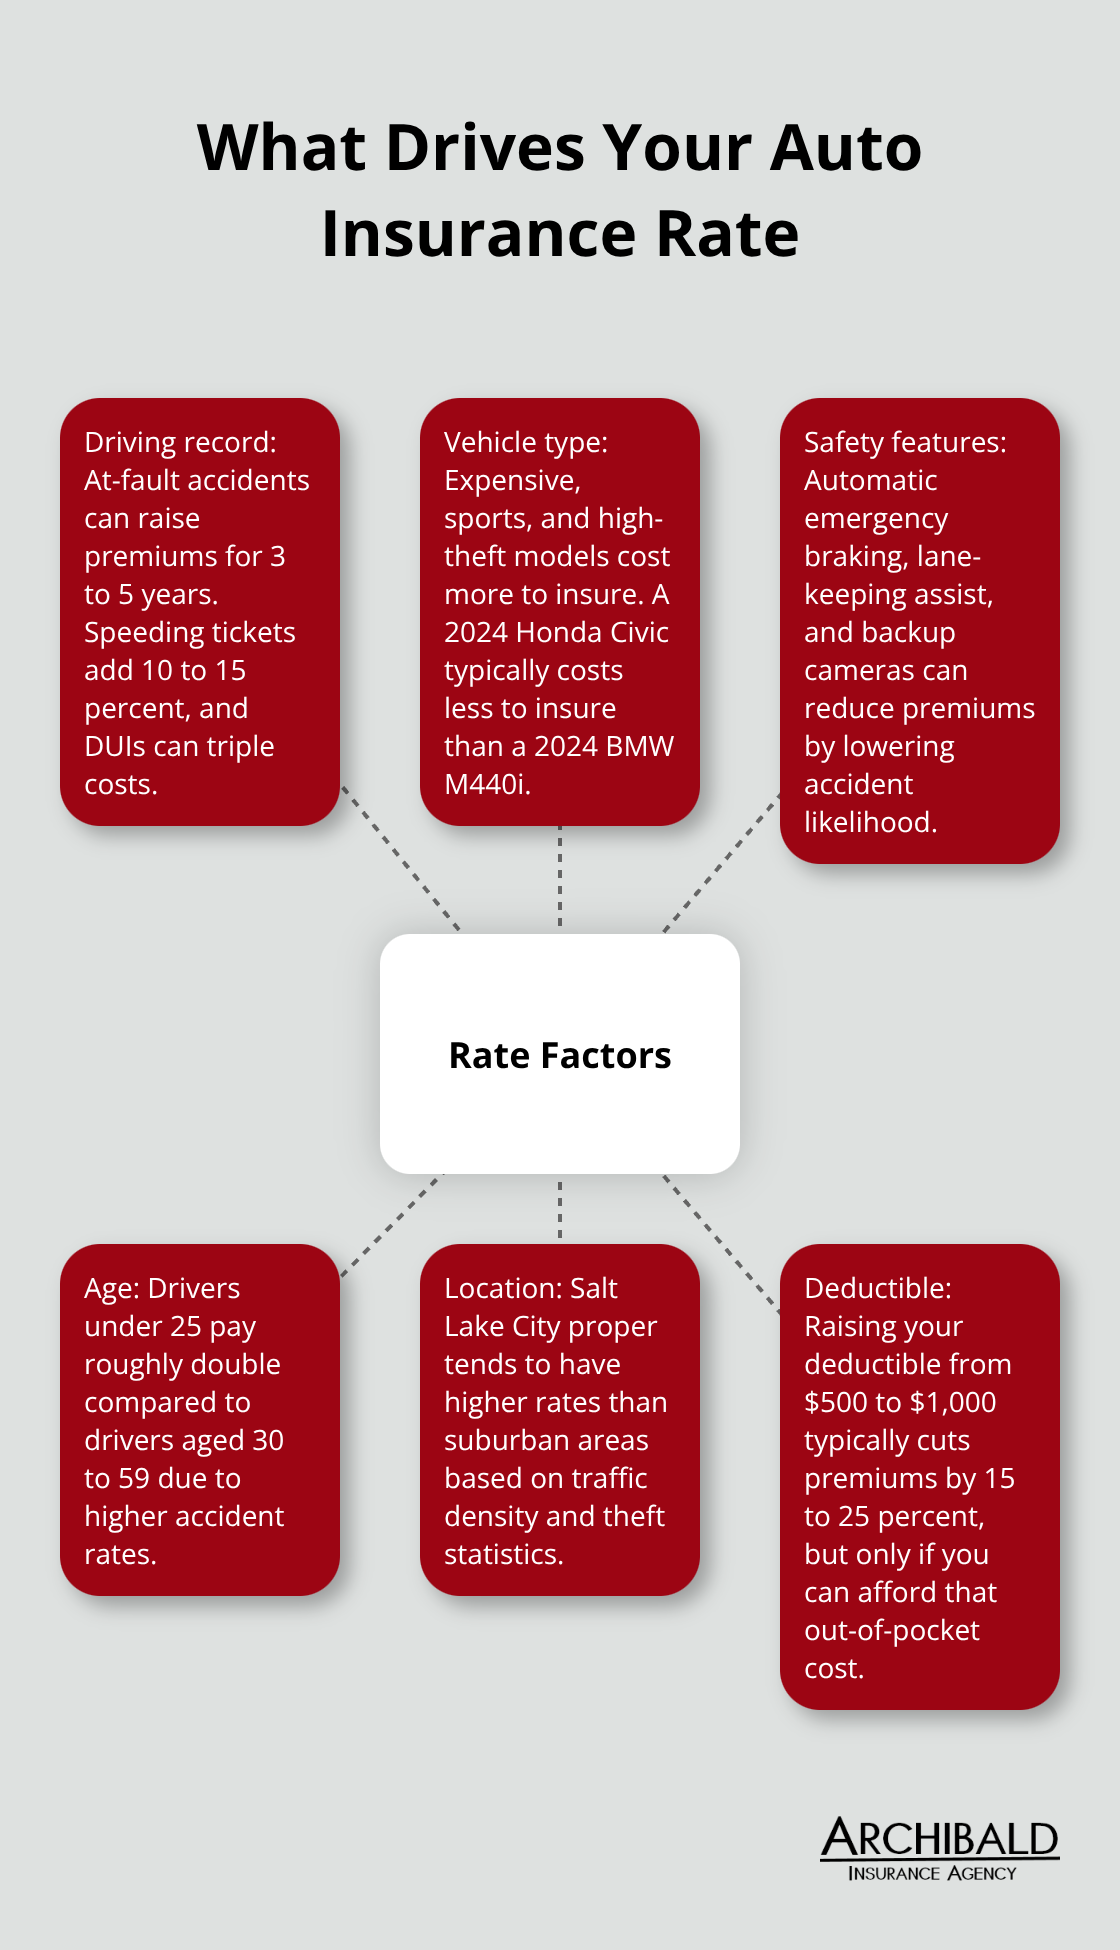
Your driving record is the single most important factor in determining your premium, and insurance companies treat it like a financial report card. At-fault accidents often increase your rates as they are an indicator of increased future risk, with increases typically lasting between 3 and 5 years. Speeding tickets add 10 to 15 percent to your premium, while DUI convictions can triple your costs or get you dropped entirely. Utah insurers keep these violations on your record for three to five years, so a clean driving history saves you thousands of dollars over time.
Vehicle Type and Safety Features Impact Your Costs
The vehicle you drive matters just as much as how you drive it. Insurers charge more for expensive vehicles, sports cars, and models with high theft rates because they cost more to repair or replace. A 2024 Honda Civic costs significantly less to insure than a 2024 BMW M440i, even if both drivers have identical records.
Safety features lower your premium substantially. Automatic emergency braking, lane-keeping assist, and backup cameras reduce your premium because they lower accident likelihood. Check your vehicle’s safety ratings on the National Highway Traffic Safety Administration website before buying, and mention available safety features when getting quotes.
Age, Location, and Deductible Shape Your Final Rate
Drivers under 25 pay roughly double what drivers aged 30 to 59 pay because younger drivers have statistically higher accident rates. Your location within Utah also affects your premium-Salt Lake City proper carries higher rates than suburban areas based on traffic density and theft statistics in your zip code.
Your deductible choice directly controls your monthly payment. Raising your deductible from $500 to $1,000 typically cuts your premium by 15 to 25 percent, but only if you can actually afford to pay that amount when an accident happens. Sit down with actual numbers rather than guessing at what you can afford.
If you have $2,000 in emergency savings, a $1,000 deductible makes sense (you protect yourself while lowering costs). If you have $500 total, that $500 deductible protects you from financial disaster despite the higher monthly cost.
These rate factors aren’t random-understanding them gives you real leverage when comparing quotes and identifying where you can actually reduce your costs.
How to Actually Cut Your Auto Insurance Costs
Bundle Policies for Substantial Savings
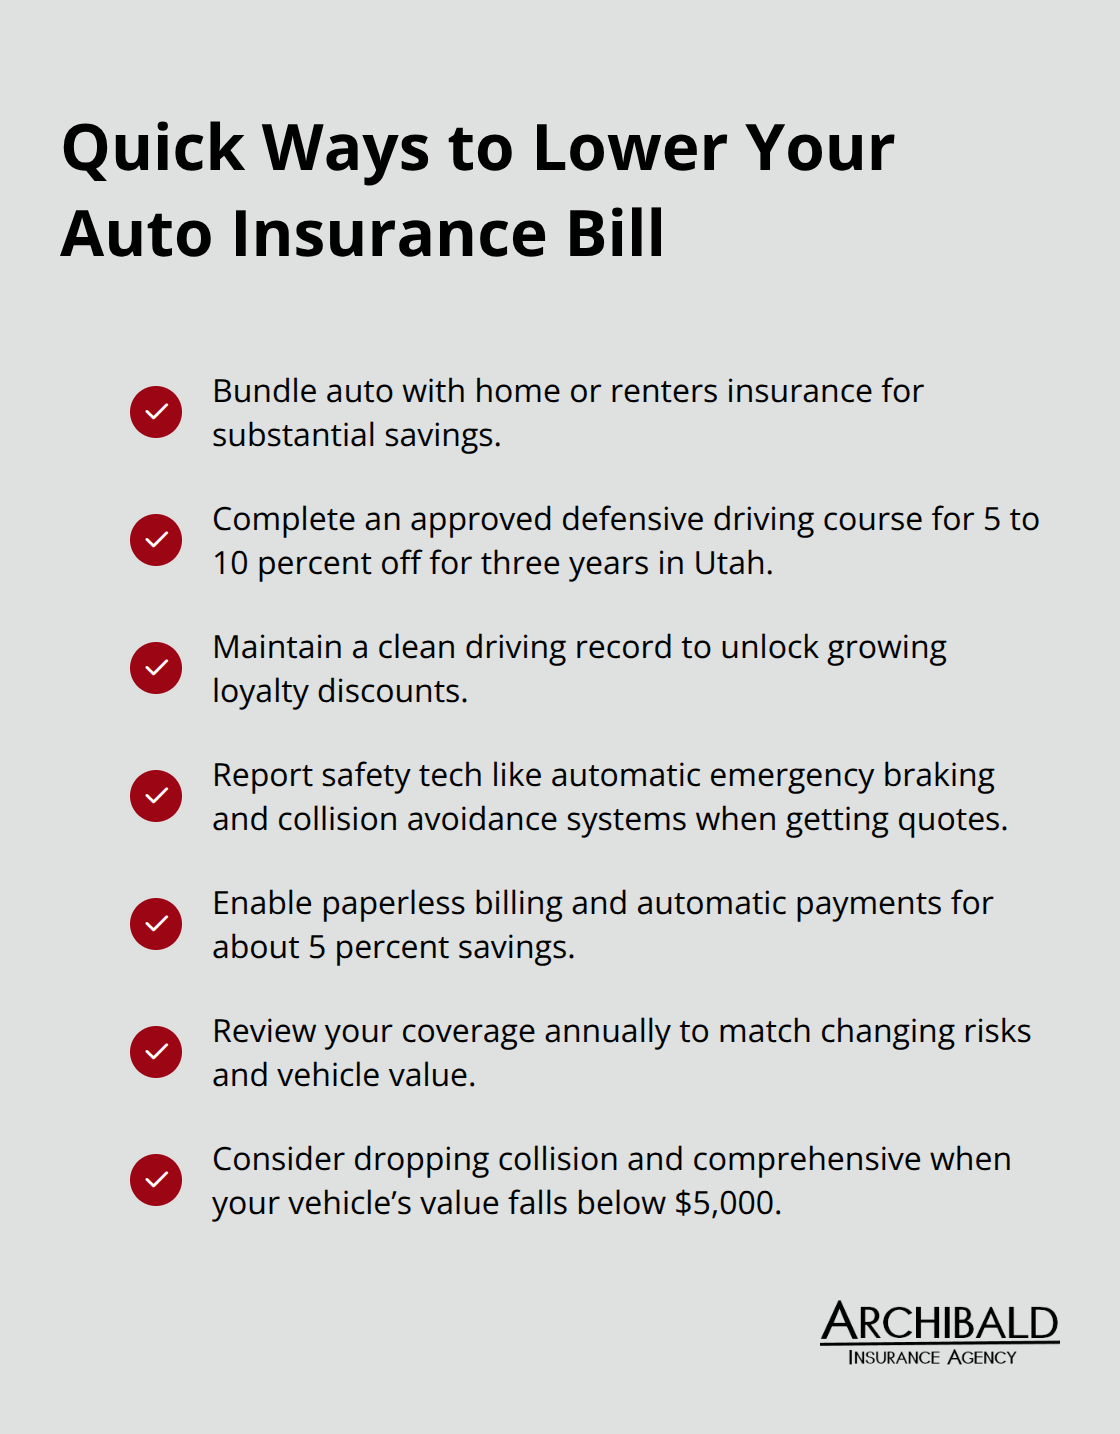
Combining your auto policy with home or renters insurance remains one of the fastest ways to lower your premium. Bundle policies for substantial savings by combining your coverage with most insurers, which means a driver paying $1,200 annually for auto coverage could save $180 to $300 by adding home insurance to the same carrier. The math works even if your home insurance costs slightly more elsewhere because the auto discount typically exceeds any premium difference. Archibald Insurance Agency helps clients identify which carriers offer the best bundling deals for their specific situation, since discount percentages vary significantly between insurers.
Stack Safety and Good Driver Discounts
Safety and good driver discounts layer on top of bundling to create substantial savings. Completing an approved defensive driving course cuts your premium by 5 to 10 percent and remains valid for three years in Utah, making the few hours of online training worth several hundred dollars in savings. Insurers also reward clean driving records with loyalty discounts that grow year after year, so avoiding even one at-fault accident protects your wallet far beyond the immediate consequences.
If your vehicle has automatic emergency braking, collision avoidance systems, or other safety technology, mention these features specifically when requesting quotes (not all agents automatically apply these discounts). Paperless billing and automatic payments typically add another 5 percent savings, cost nothing to implement, and prevent you from missing payment deadlines.
Review Your Coverage Annually
Annual coverage reviews prevent you from overpaying for protection you no longer need. Vehicle value drops roughly 15 to 20 percent in the first year and continues declining, so comprehensive and collision coverage becomes less valuable as your car ages. Once your vehicle reaches five to seven years old and drops below $5,000 in value, the premium you pay for collision often exceeds what the insurance would actually pay out, making it financially irrational to carry.
Simultaneously, your life circumstances change-marriage, home purchases, or business ownership create new liability risks that require higher limits. Reviewing coverage annually prevents both overpaying for unnecessary protection and underinsuring against genuine risks. This review process takes roughly 30 minutes and directly addresses the rate factors discussed earlier (ensuring your deductibles, limits, and coverage types match your actual financial situation rather than choices you made years ago).
Final Thoughts
Auto insurance in Salt Lake City requires you to balance protection with affordability, and the decisions you make today directly impact your financial security for years to come. Your driving record, vehicle type, and deductible choices form the foundation of your premium, but they’re not fixed-a clean driving record going forward, bundling policies, and completing a defensive driving course can cut your costs substantially. Annual reviews catch situations where you’re overpaying for unnecessary coverage or underinsuring against real risks.
Getting personalized quotes matters because discount percentages and coverage options vary significantly between carriers. What saves one driver hundreds of dollars might offer minimal benefit to another driver with different circumstances, so comparing quotes from multiple insurers takes time upfront but reveals real savings opportunities you’d miss otherwise. Your specific situation determines which coverage types, limits, and deductibles actually make financial sense.
Contact Archibald Insurance Agency to discuss your coverage needs and discover what auto insurance in Salt Lake actually costs for your situation. Our team handles the comparison work so you don’t have to, and we explain your options in straightforward language rather than insurance jargon. Protecting your vehicle and finances starts with making informed decisions today.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation


