
SLC Risk Advisor: Proactive Guidance From Local Agents
Insurance decisions in Salt Lake City aren’t one-size-fits-all. Your home faces different risks than your neighbor’s, your business has unique coverage needs, and your family’s protection requires careful planning.
An SLC risk advisor who knows your community can spot gaps you might miss and guide you toward solutions that actually fit your life. At Archibald Insurance Agency, we work with Utah families and business owners to build protection strategies that make sense for where you live and what matters most to you.
Why Local Agents Get Utah Right
Utah’s Geography Shapes Your Insurance Needs
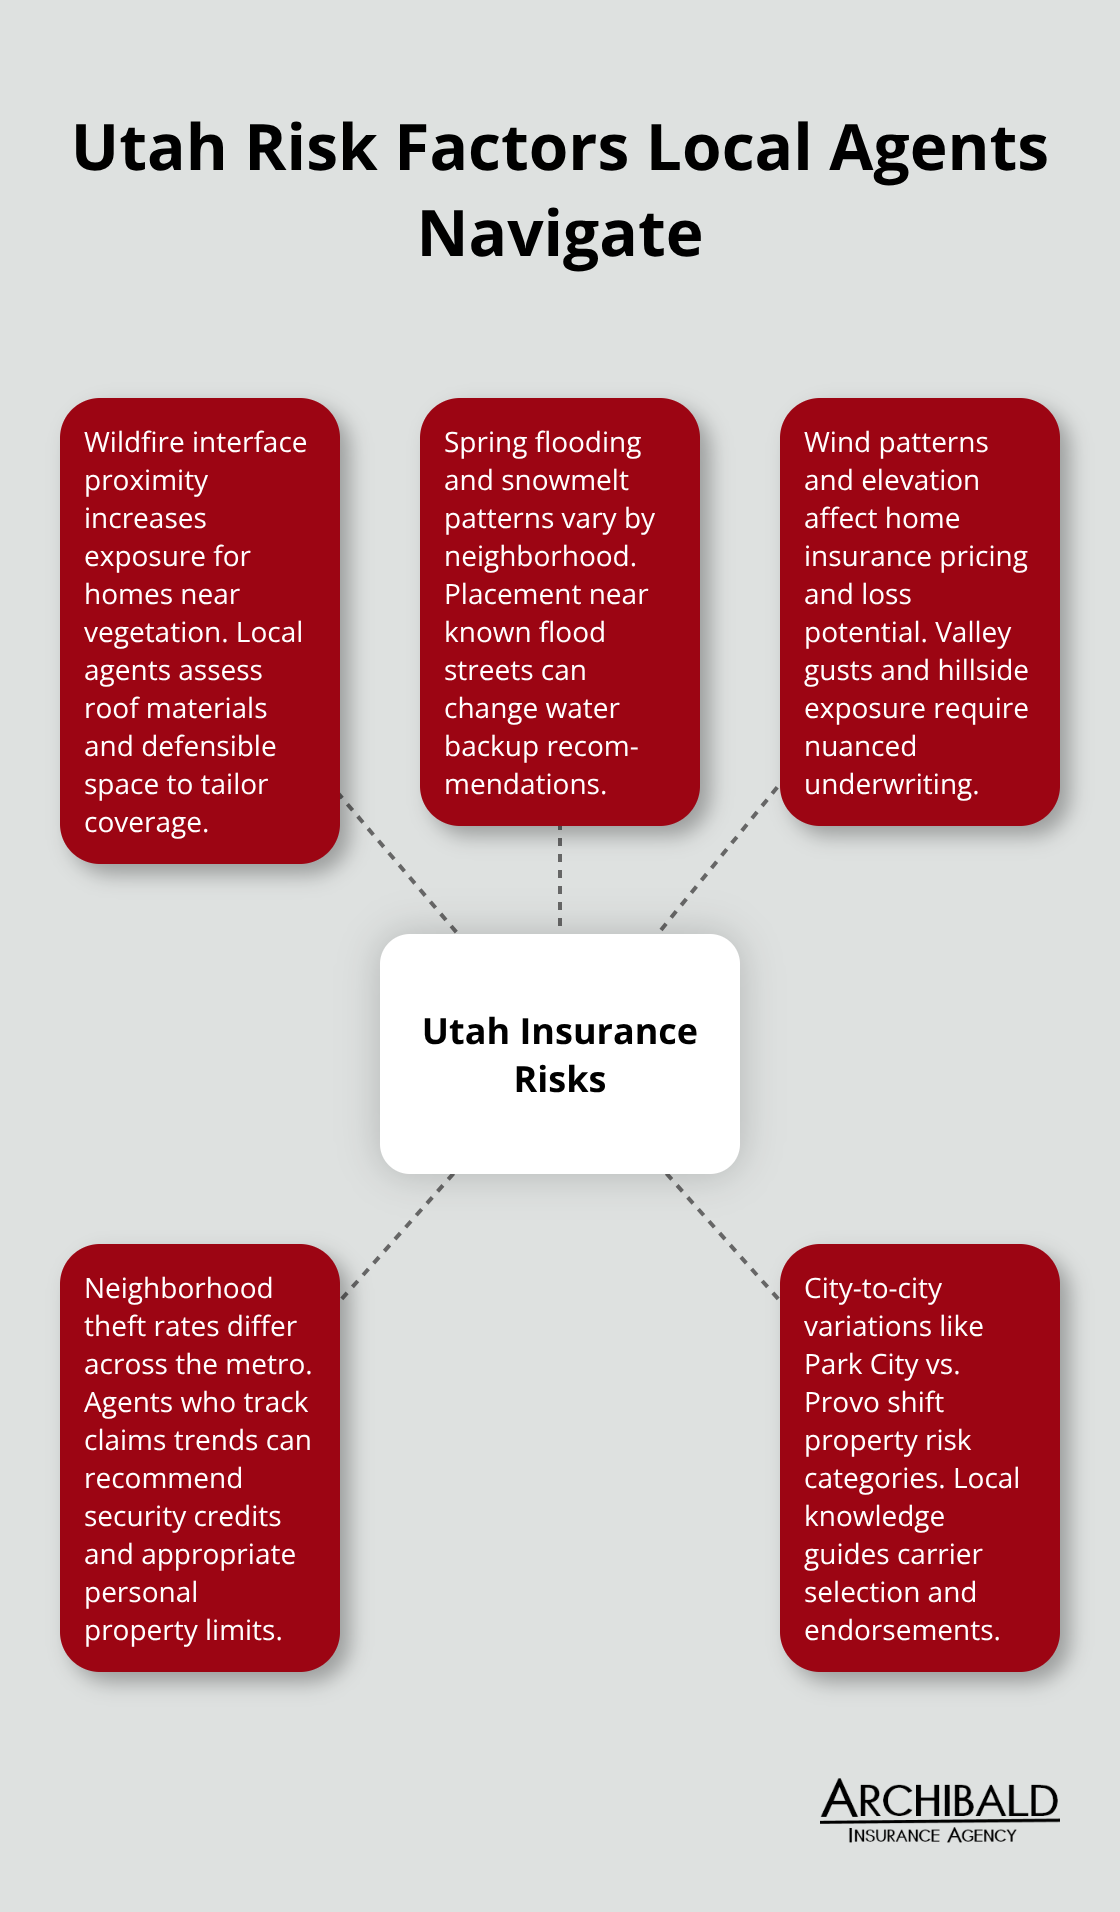
Utah’s insurance landscape demands more than generic solutions. Salt Lake City homeowners face wildfire exposure in Utah that Denver residents don’t encounter, while Park City properties sit in a different risk category than Provo homes. A national call center agent working from a script cannot account for these differences. Local independent agents understand the specific hazards your address faces, from spring flooding in certain neighborhoods to the particular wind patterns that affect home insurance rates across the valley. Knowledge of which streets flood during heavy snow melt, which areas see higher theft rates, and how elevation affects your premiums comes from working with Utah families year after year and seeing how real risks play out in our community.
Why National Insurers Fall Short
Large national insurers optimize for volume and standardization. They apply broad underwriting criteria that often don’t reflect local conditions, which means you either overpay or get stuck with inadequate coverage. Independent agents represent multiple carriers, giving you access to companies willing to price fairly for Utah-specific situations. When your home sits near a wildland interface, an independent agent can find carriers that properly assess that risk rather than slapping on a blanket surcharge.
The Advantage of Local Relationships
The relationship matters significantly. A local agent builds trust through presence and accountability-you can visit the office, speak with someone who lives in your community, and know that the agency is invested in your long-term satisfaction rather than hitting quarterly targets. That reliability creates a foundation where you can be honest about your actual needs, budget constraints, and concerns without worrying that you’re just a policy number in a system designed to move you along quickly. This foundation of trust becomes especially valuable when you need to adjust your coverage or file a claim.
Stop Guessing About Your Coverage
Coverage Gaps Cost Money When Claims Happen
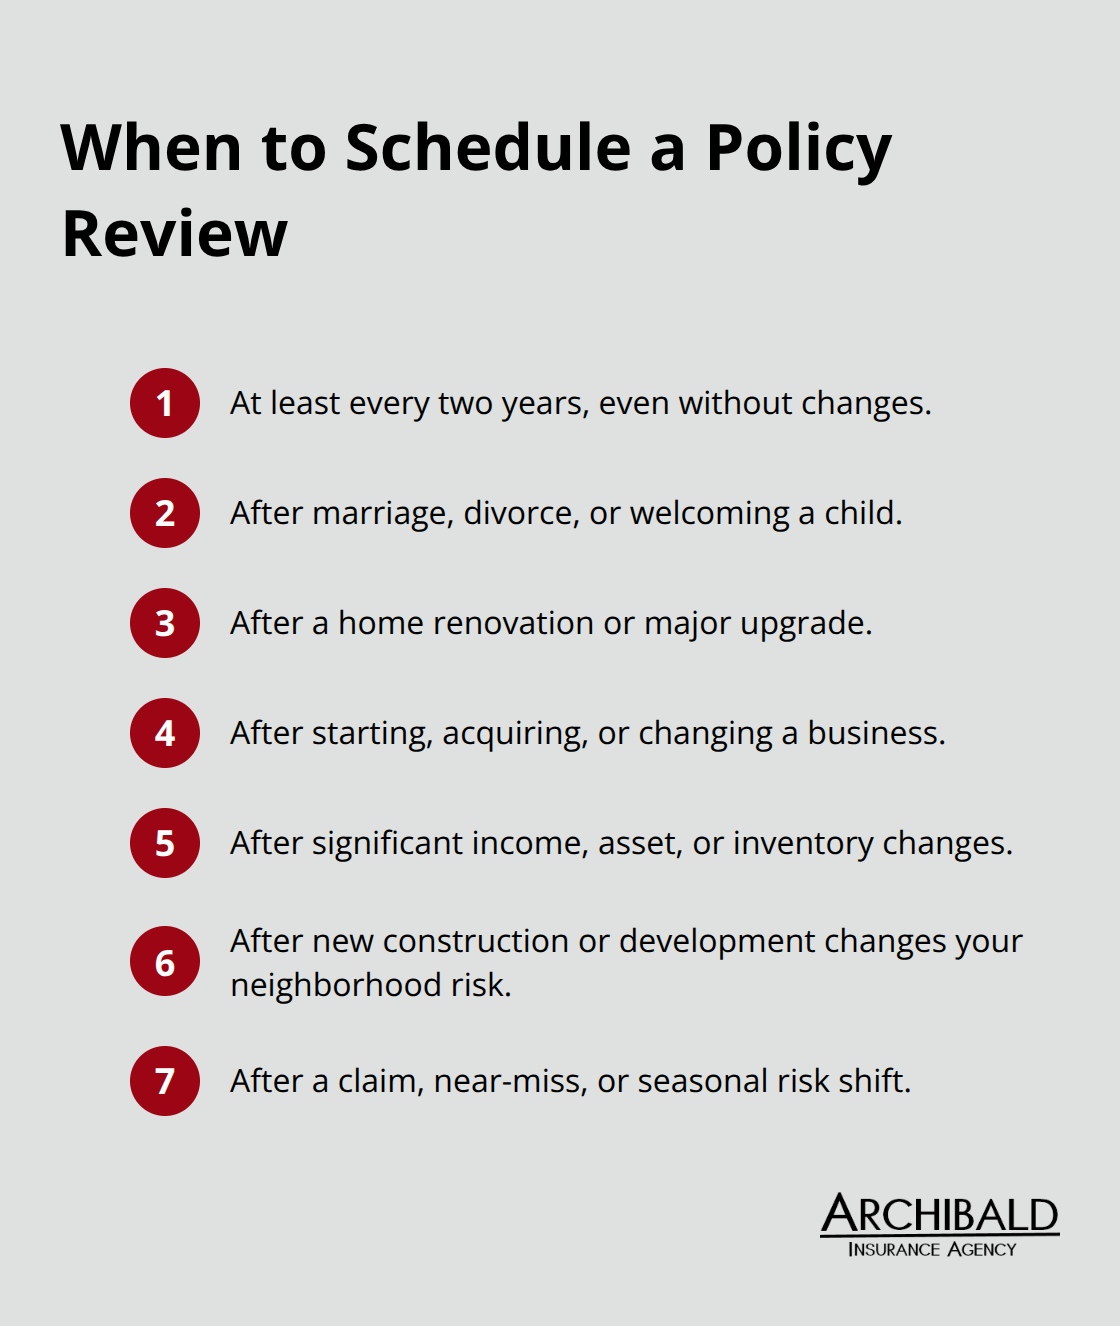
Most people avoid reviewing their insurance until something goes wrong. That’s a costly mistake in Utah, where your risk profile shifts every few years. New construction in your neighborhood, a promotion that increases your home value, or a shift in your business operations all demand coverage adjustments that rarely happen automatically. Families discover coverage gaps only after a claim gets denied or they realize their limits are dangerously low. The solution isn’t waiting for disaster-schedule a comprehensive policy review at least every two years, or immediately after major life changes like marriage, home renovation, or starting a business. During these reviews, an independent agent compares your current coverage against what you actually own and what you genuinely risk losing.
Utah Homeowners Need Current Replacement Cost Numbers
Utah homeowners should examine their dwelling coverage limits against current replacement costs, since construction materials and labor have increased significantly since many policies were written. Ask your agent to run a detailed inventory of your home’s square footage, upgrades, and contents value, then verify your limits match those numbers. This step alone prevents thousands of dollars in underinsurance when you file a claim.
Wildfire Risk Demands Specific Property Evaluation
Utah’s wildfire risk has intensified across the state. The Utah Division of Forestry reports that structures near wildland interfaces face substantially higher exposure than properties in developed areas. Your home’s proximity to vegetation, roof material composition, and defensible space around your foundation all factor into risk assessment, yet most national carriers use crude proximity rules rather than detailed property evaluation. A local agent understands these nuances and can recommend appropriate coverage before fire season arrives.
Winter Weather and Seasonal Business Changes
Winter weather presents different challenges: heavy snow, ice dam damage, and weight-related roof failures occur regularly in Salt Lake Valley neighborhoods. An agent who knows your area identifies which neighborhoods experience the worst spring flooding during snow melt and recommends appropriate water backup coverage or sump pump protection. For business owners, seasonal staffing changes, inventory fluctuations, and weather-related closures require mid-year policy adjustments that most entrepreneurs overlook. Rather than hoping your existing coverage handles these situations, work with an agent who asks specific questions about your operations during different seasons and adjusts your limits accordingly before problems arise.
Moving From Reactive to Proactive Protection
This shift from reactive to proactive protection requires an agent who takes time to understand your specific circumstances. That’s where the guidance of a local independent agency becomes invaluable-not just for identifying what you need today, but for anticipating what you’ll need tomorrow.
How Your Insurance Strategy Gets Built
Questions That Reveal What You Actually Need
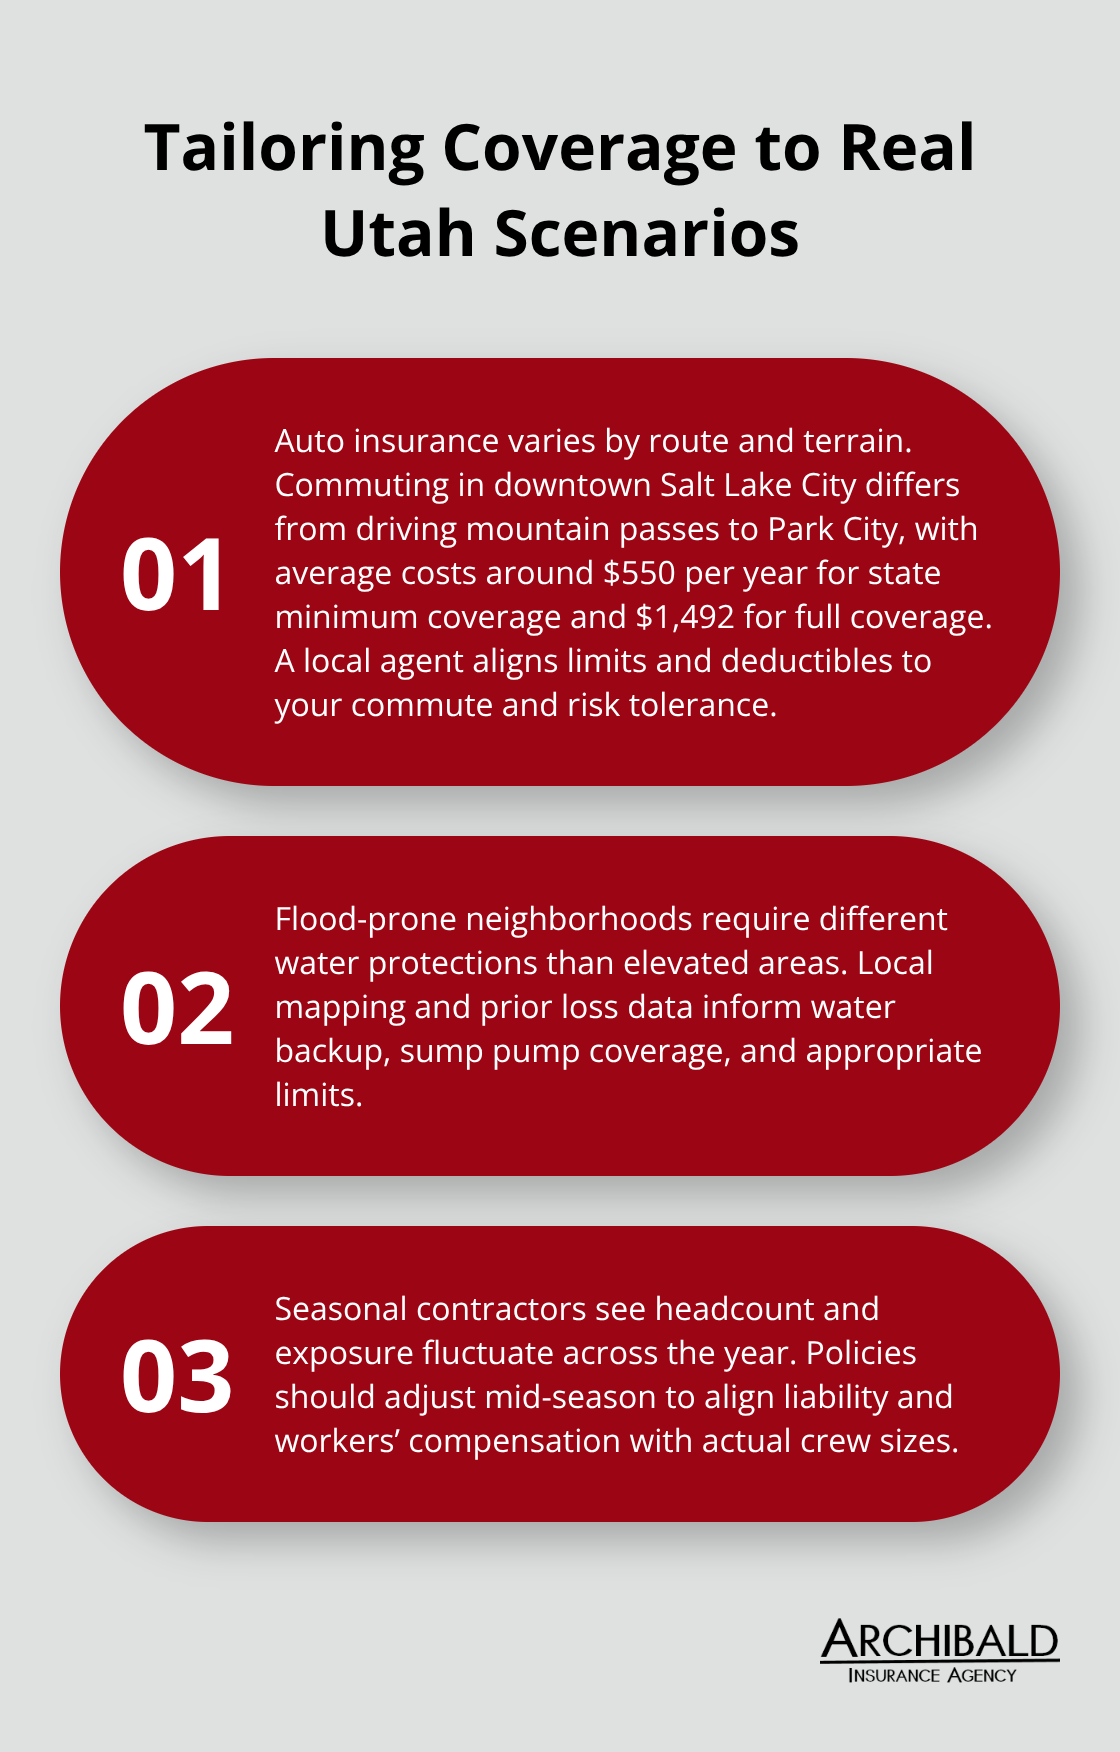
At Archibald Insurance Agency, we start by asking questions that matter: What do you actually own? What would it cost to replace everything if disaster struck today? How much financial risk can your family absorb without hardship? These conversations reveal what insurance companies call exposure, but what really matters is whether your protection matches your actual life. Utah’s varied landscape means your auto insurance needs differ dramatically depending on whether you commute through downtown Salt Lake City or drive mountain passes to Park City, with average costs ranging around $550 yearly for state minimum coverage or $1,492 for full coverage. A homeowner in a flood-prone neighborhood requires different water coverage than someone on elevated terrain. A contractor operating seasonal crews needs coverage that adjusts as headcount fluctuates throughout the year.
Matching Your Circumstances to the Right Carriers
Rather than applying generic formulas, we examine your specific circumstances and match you with carriers that price fairly for your exact risk profile. This approach costs less than overpaying national insurers while delivering coverage that actually protects what matters. We represent multiple insurance carriers, which means we can find companies willing to price fairly for Utah-specific situations instead of applying blanket surcharges that don’t reflect your actual risk.
Building Protection Within Your Budget
Budget constraints shape every real insurance decision, yet most agencies treat cost as secondary to coverage. We treat it differently. When you tell us your budget limit, we work backward to maximize protection within that number instead of recommending everything and hoping you’ll figure out what to cut. This means identifying which coverages are non-negotiable for your situation and which can wait until your financial position improves. A young family might prioritize life insurance with lower limits on auto coverage, then adjust both as income increases. A business owner might concentrate on liability protection initially, then add workers compensation as hiring accelerates. We also explain what each premium dollar actually buys, so you understand whether you’re paying for protection you genuinely need or coverage that sounds good but won’t protect you from realistic Utah risks.
Staying Current as Your Life Changes
Once policies are in place, the relationship continues. We contact clients annually to review whether life changes demand adjustments, whether better rates exist with different carriers, and whether coverage limits still match current replacement costs. This ongoing attention catches problems before claims happen and keeps your protection current as circumstances shift.
Final Thoughts
Insurance protection in Salt Lake City works best when a local SLC risk advisor understands both your circumstances and your community’s specific risks. National call centers miss problems that someone who knows your neighborhood, your business, and your family’s situation catches immediately. That difference separates coverage that sounds adequate from protection that actually works when you need it.
We at Archibald Insurance Agency built our practice on this principle as a family-owned independent agency representing multiple insurance carriers. This means we find solutions that fit your actual needs and budget rather than pushing whatever generates the highest commission. We work with Utah families and business owners across auto, home, business, and life insurance, handling everything from routine policy reviews to complex coverage questions that require local knowledge and accountability.
Your protection starts with guidance from someone who knows Utah’s insurance landscape and knows you personally. Contact us to schedule a comprehensive policy review and see how local expertise strengthens your protection strategy.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation


