
Compare Auto Insurance Quotes: Find Your Best Rate
Auto insurance rates vary dramatically from one company to the next, and most drivers overpay simply because they don’t compare quotes. We at Archibald Insurance Agency help Utah residents find better rates by understanding what insurers actually look at when they price your policy.
The difference between your current rate and your best available rate could be hundreds of dollars annually. This guide walks you through comparing auto insurance quotes effectively so you can make an informed decision.
How Auto Insurance Quotes Work
Understanding What Insurers Actually Look at When Pricing Your Policy
An auto insurance quote reflects dozens of data points that insurers weigh differently. When you request a quote, the insurer isn’t just guessing-they’re calculating risk based on concrete information about you, your vehicle, and your driving patterns. Your driving history carries enormous weight.
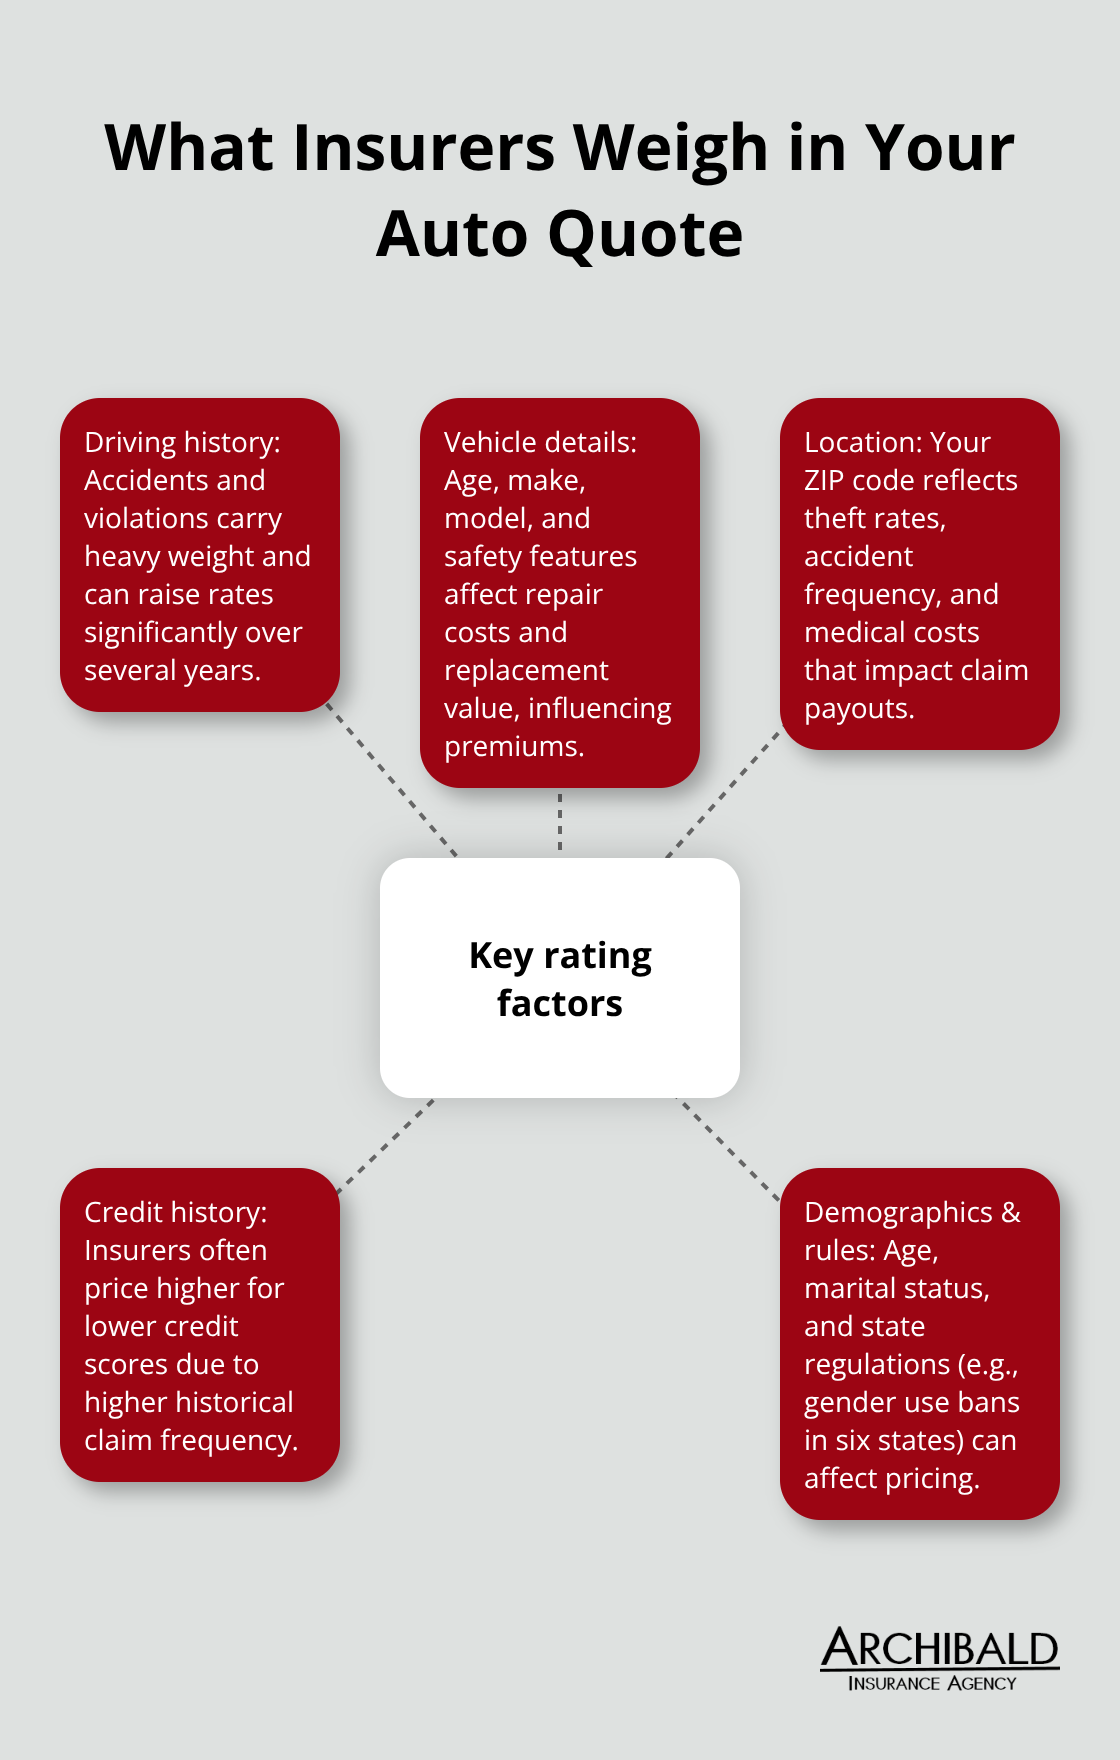
A single accident or traffic violation can increase your premium by about 25 percent, depending on the insurer and the severity of the incident. According to data from comparison platforms, a 30-year-old Florida driver with good credit might see full-coverage quotes ranging from $128 per month to $301 per month across different insurers-a difference of over $2,000 annually.
Your vehicle’s age, make, model, and safety features all factor into the calculation. A newer car with advanced safety technology typically costs more to insure than an older vehicle, but repair costs and replacement value also influence the premium. Location matters significantly too. Your ZIP code determines everything from theft rates in your area to the cost of medical care in your region, which directly impacts claim payouts. In Utah, rates have climbed even for drivers with clean records. Your credit history also plays a role-insurers have found that people with lower credit scores file more claims, so they adjust premiums accordingly. However, six states (California, Hawaii, Massachusetts, Michigan, North Carolina, and Pennsylvania) ban insurers from using gender as a rating factor, though most other states allow it.
Why the Same Coverage Costs Different Amounts
Two insurers quoting identical coverage limits on the same vehicle for the same driver will often produce different numbers because they use proprietary risk models. State Farm, USAA, Geico, Progressive, and Bear River Mutual all operate in Utah but price policies using different algorithms and underwriting standards. This is precisely why comparing quotes matters. A driver in Salt Lake City might pay $103 per month with State Farm for coverage that costs $130 per month with USAA, even though both policies provide the same protection.
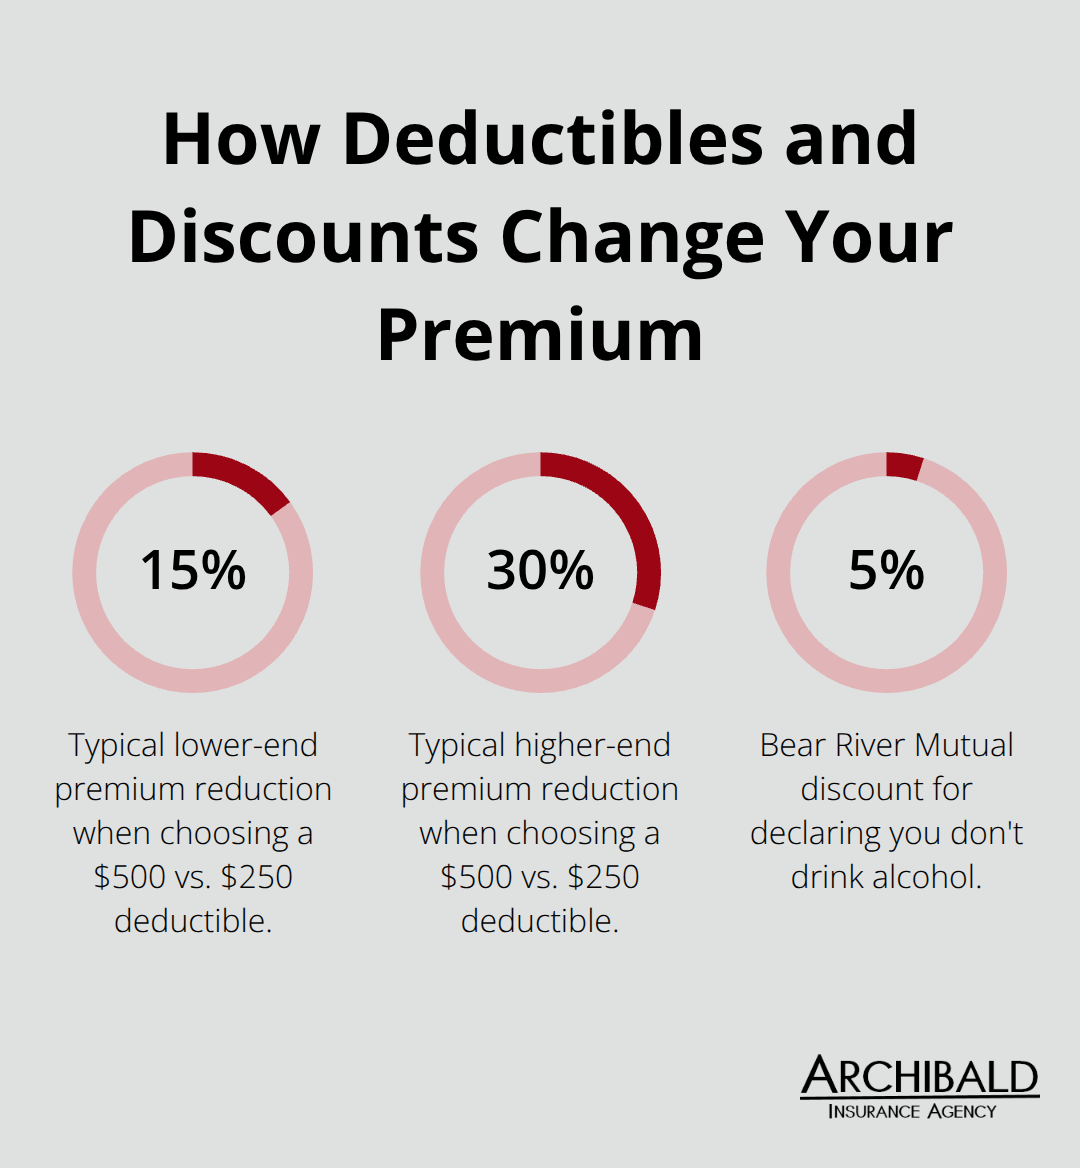
The deductible you choose dramatically affects your quote. Selecting a $500 deductible instead of $250 typically lowers your premium by 15 to 30 percent, but it means you’ll pay more out of pocket if you file a claim. Bear River Mutual offers a 5 percent discount if you declare that you don’t drink alcohol, demonstrating how insurers create niche pricing strategies.
How Bundling and Discounts Shape Your Final Rate
Bundling auto insurance with home or renters insurance can reduce your total cost significantly. State Farm, Allstate, and Nationwide commonly offer substantial discounts when you combine multiple policies with them. Multi-car discounts, good-driver discounts, and loyalty discounts also vary by insurer. Some companies reward safe driving with usage-based programs that monitor your actual habits, potentially lowering your rate if you drive safely and infrequently. These variations mean that the lowest quote doesn’t always represent the best value-you need to compare what each insurer actually offers for the price they quote.
How to Gather and Compare Your Quotes
Organize Your Information Before Requesting Quotes
Getting accurate quotes requires you to have the right information ready before you start requesting them. Collect your vehicle identification number (VIN), current insurance declarations page if you have one, and your driving record. You’ll need your ZIP code, annual mileage estimate, and the specific coverage limits you’re considering. Insurers ask for your date of birth, marital status, education level, and credit history because these factors influence pricing.
Utah residents should know that rates are climbing even for drivers with clean records, so getting multiple quotes now could save you substantially compared to what you’d pay six months from now. The more details you provide upfront, the more reliable your quotes will be. Providing incomplete information forces insurers to estimate, which can produce quotes that don’t reflect your actual risk profile.
Request Quotes From Multiple Carriers
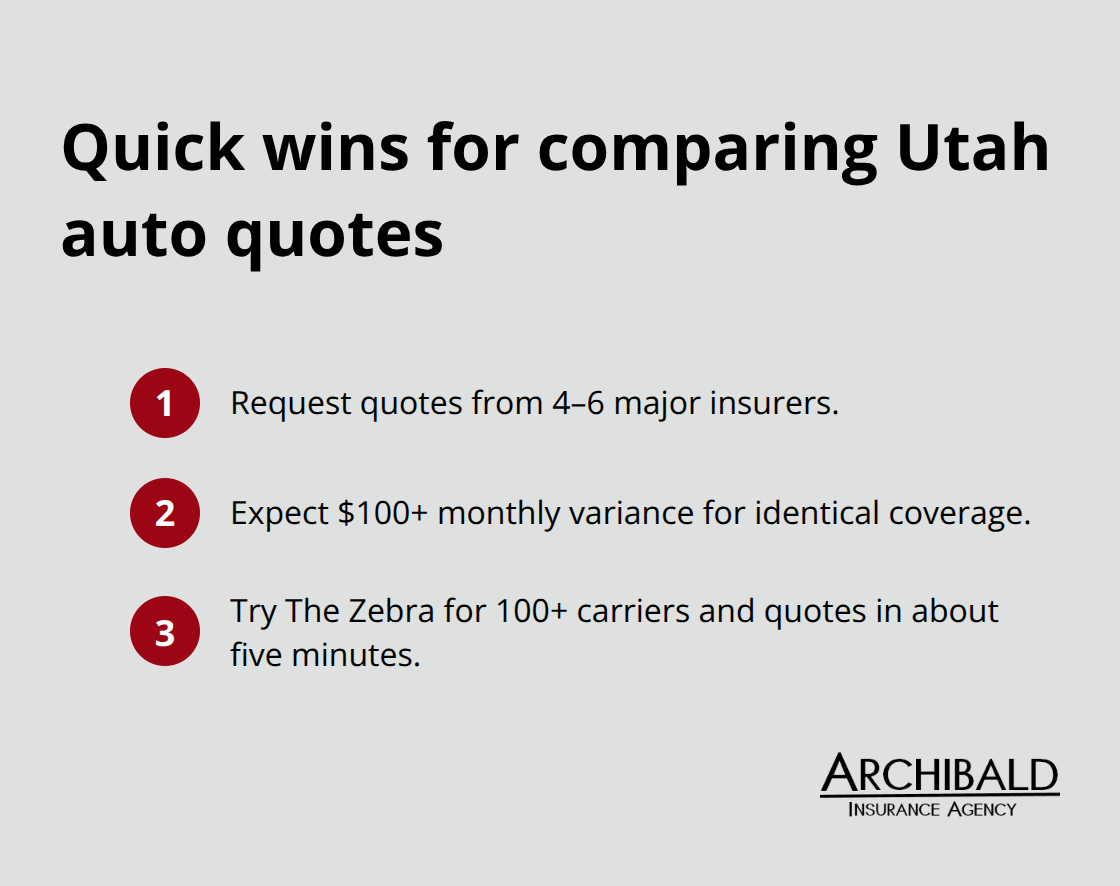
Request quotes from at least four to six major insurers operating in Utah. State Farm, USAA, Geico, Progressive, and Bear River Mutual all serve Utah drivers, and their prices for identical coverage can differ by over $100 monthly. Use online quote tools from these carriers directly, but also consider comparison platforms like The Zebra, which pulls quotes from 100+ carriers and has delivered over 74 million quotes to date. The Zebra reports that personalized quotes typically arrive within five minutes after you answer their quick questions.
Compare Coverage, Deductibles, and Discounts Side by Side
When comparing quotes side by side, verify that coverage limits, deductibles, and add-ons match exactly across all quotes. A $128 monthly premium with a $1,000 deductible is not the same as a $98 monthly premium with a $2,500 deductible. Review what discounts each insurer applies to your situation-bundling your auto policy with homeowners coverage through the same company can drop your total cost substantially, particularly with State Farm, Allstate, or Nationwide.
Pay attention to what each insurer includes in their quote: some offer accident forgiveness, usage-based discounts, or low-mileage discounts that others don’t. The lowest price often comes with trade-offs in claims handling quality or repair network access, so don’t stop at comparing numbers. Check recent customer reviews on Trustpilot or the National Association of Insurance Commissioners website to understand how each insurer handles claims in your area.
Get Expert Guidance on Your Final Decision
Contact an independent agent who can help you understand coverage nuances and identify discounts you might miss on your own. An agent reviews your specific situation and explains how different deductibles, coverage limits, and bundling options affect your total cost. This guidance becomes especially valuable when you’re deciding between quotes that appear similar in price but differ significantly in what they cover.
What Really Drives Your Auto Insurance Price
Driving History Sets the Foundation for Your Rate
Your driving record is the single most important factor determining your rate, and insurers treat it with brutal honesty. Traffic violations carry significant weight in premium calculations. Progressive and State Farm, two major Utah carriers, both maintain detailed driving records and adjust pricing accordingly.
If you’ve had multiple incidents within the past three to five years, expect quotes that are substantially higher than drivers with clean records. The impact of accidents and violations diminishes over time. Most insurers reduce the penalty after three years, and some forgive incidents after five years entirely. This means that even if your current quotes seem expensive due to past mistakes, shopping around in a few years could yield dramatically lower rates.
Vehicle Characteristics and Type Shape Your Premium
Your vehicle’s characteristics shape your premium in ways many drivers overlook. Newer cars with advanced safety features and backup cameras typically cost more to insure because repair costs are higher, but some insurers reward safety technology with discounts that offset the increased replacement value. An older, paid-off sedan will almost always cost less to insure than a newer sports car or truck, particularly if you only carry liability coverage.
The make and model matter significantly too-a Honda Civic costs considerably less to insure than a BMW or luxury vehicle because replacement parts are cheaper and theft rates differ. Your location within Utah affects pricing more than many drivers realize. Salt Lake City residents pay different rates than those in rural counties because urban areas have higher accident rates and medical costs.
Mileage and Driving Patterns Influence Your Quote
Annual mileage influences your quote substantially. Drivers who commute 50 miles daily pay more than those who work from home and drive only occasionally. Some insurers now offer usage-based insurance programs that monitor your actual driving habits through a smartphone app or plug-in device. These programs work best for low-mileage drivers in Utah who can demonstrate that they rarely use their vehicles during peak traffic hours.
Final Thoughts
Comparing auto insurance quotes reveals exactly how different insurers value your risk, and those differences add up to hundreds of dollars annually. Utah drivers who take time to compare auto insurance quotes from multiple carriers consistently find better rates than those who accept their current premium without question. Your driving history, vehicle type, location, and mileage all factor into pricing, but no single insurer weights these factors identically.
Once you’ve collected quotes and identified your best option, contact the insurer directly to bind coverage and confirm all details match what you reviewed. Ask about payment plans-some carriers offer discounts for paying in full or setting up automatic payments. Verify that your policy includes all the discounts you qualified for during the quoting process, since discounts sometimes don’t apply automatically.
We at Archibald Insurance Agency represent numerous carriers, which means we can access quotes and coverage options you might not find on your own (our team reviews your specific situation, explains coverage nuances, and identifies discounts tailored to your circumstances). When you need to file a claim or adjust your coverage, having an agent who knows your policy makes the process smoother. Contact Archibald Insurance Agency to discuss your auto insurance needs and discover how we can help you find coverage that protects you without overpaying.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation


