
E&O Policy Utah: What Entrepreneurs Should Know
One mistake in your business can cost thousands in legal fees and settlements. An E&O policy in Utah protects entrepreneurs like you from liability claims tied to professional errors or negligence.
At Archibald Insurance Agency, we help Utah business owners understand why this coverage matters for their specific industry. Whether you’re in consulting, real estate, or tech, the right E&O policy is your financial safety net.
What Your E&O Policy Actually Covers
Professional Liability Protection
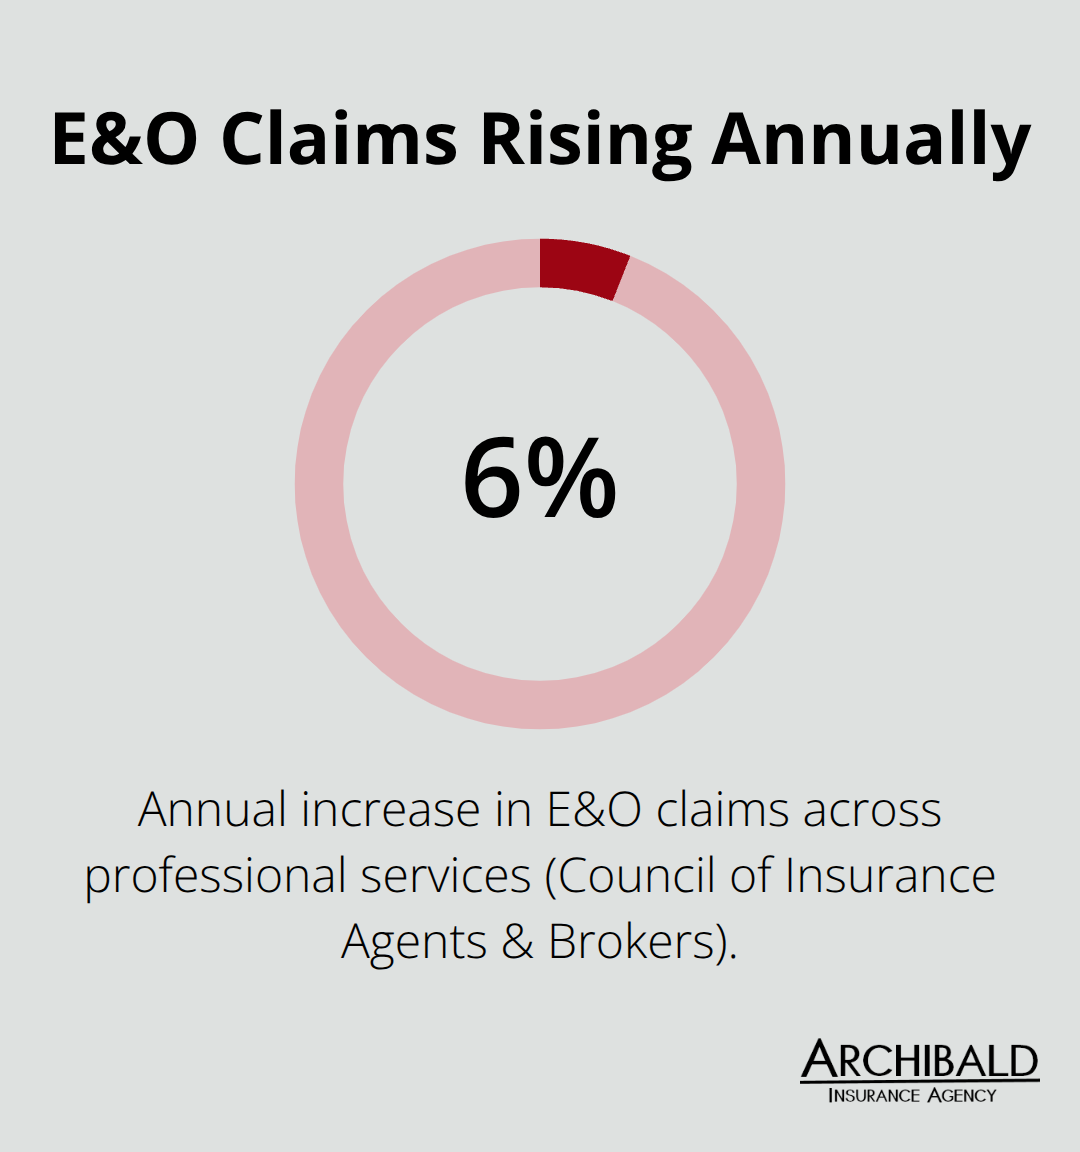
E&O insurance protects you from the financial fallout when your professional advice or work causes a client financial loss. This isn’t about covering property damage or bodily injury-it’s about protecting your reputation and bank account when someone claims you made a mistake. The Council of Insurance Agents and Brokers reports that E&O claims in professional services have increased 6% annually, making this coverage more relevant than ever for Utah entrepreneurs.
Your policy typically covers defense costs, which means the insurance company pays your legal fees before any settlement or judgment. This matters significantly because a single lawsuit can cost $50,000 to $150,000 just to defend, even if you win. The policy also covers settlements and judgments if you’re found liable, protecting your personal assets from being seized to pay damages. Expert witnesses alone can run $300 to $500 per hour, and legal expenses accumulate quickly.
Coverage for Errors and Omissions
E&O coverage addresses specific professional errors that cause client losses. If you’re a consultant who provides incorrect financial projections that lead to a client’s failed investment, your E&O policy covers that claim. Real estate agents face claims when property defects aren’t disclosed or when transactions fall through due to errors in documentation. Software developers confront claims when code fails and causes business interruption for clients.
The coverage also typically includes regulatory defense costs if a client files a complaint with a professional licensing board (which happens more frequently than most business owners realize). Claims-made policies require you to report incidents during the active policy period, even if the injury occurred years earlier. This means you need continuous coverage-a gap of even a few months can leave you vulnerable to claims that fall outside any policy period.
Why Coverage Details Matter for Your Industry
The specifics of what’s covered vary by industry, which is why working with an agency familiar with your particular field matters. Your consulting firm faces different risks than a real estate brokerage or software company. Each industry has unique exposure points that standard policies may not address completely. Understanding these nuances helps you identify gaps in your protection before a claim exposes them.
Industries That Need E&O Coverage in Utah
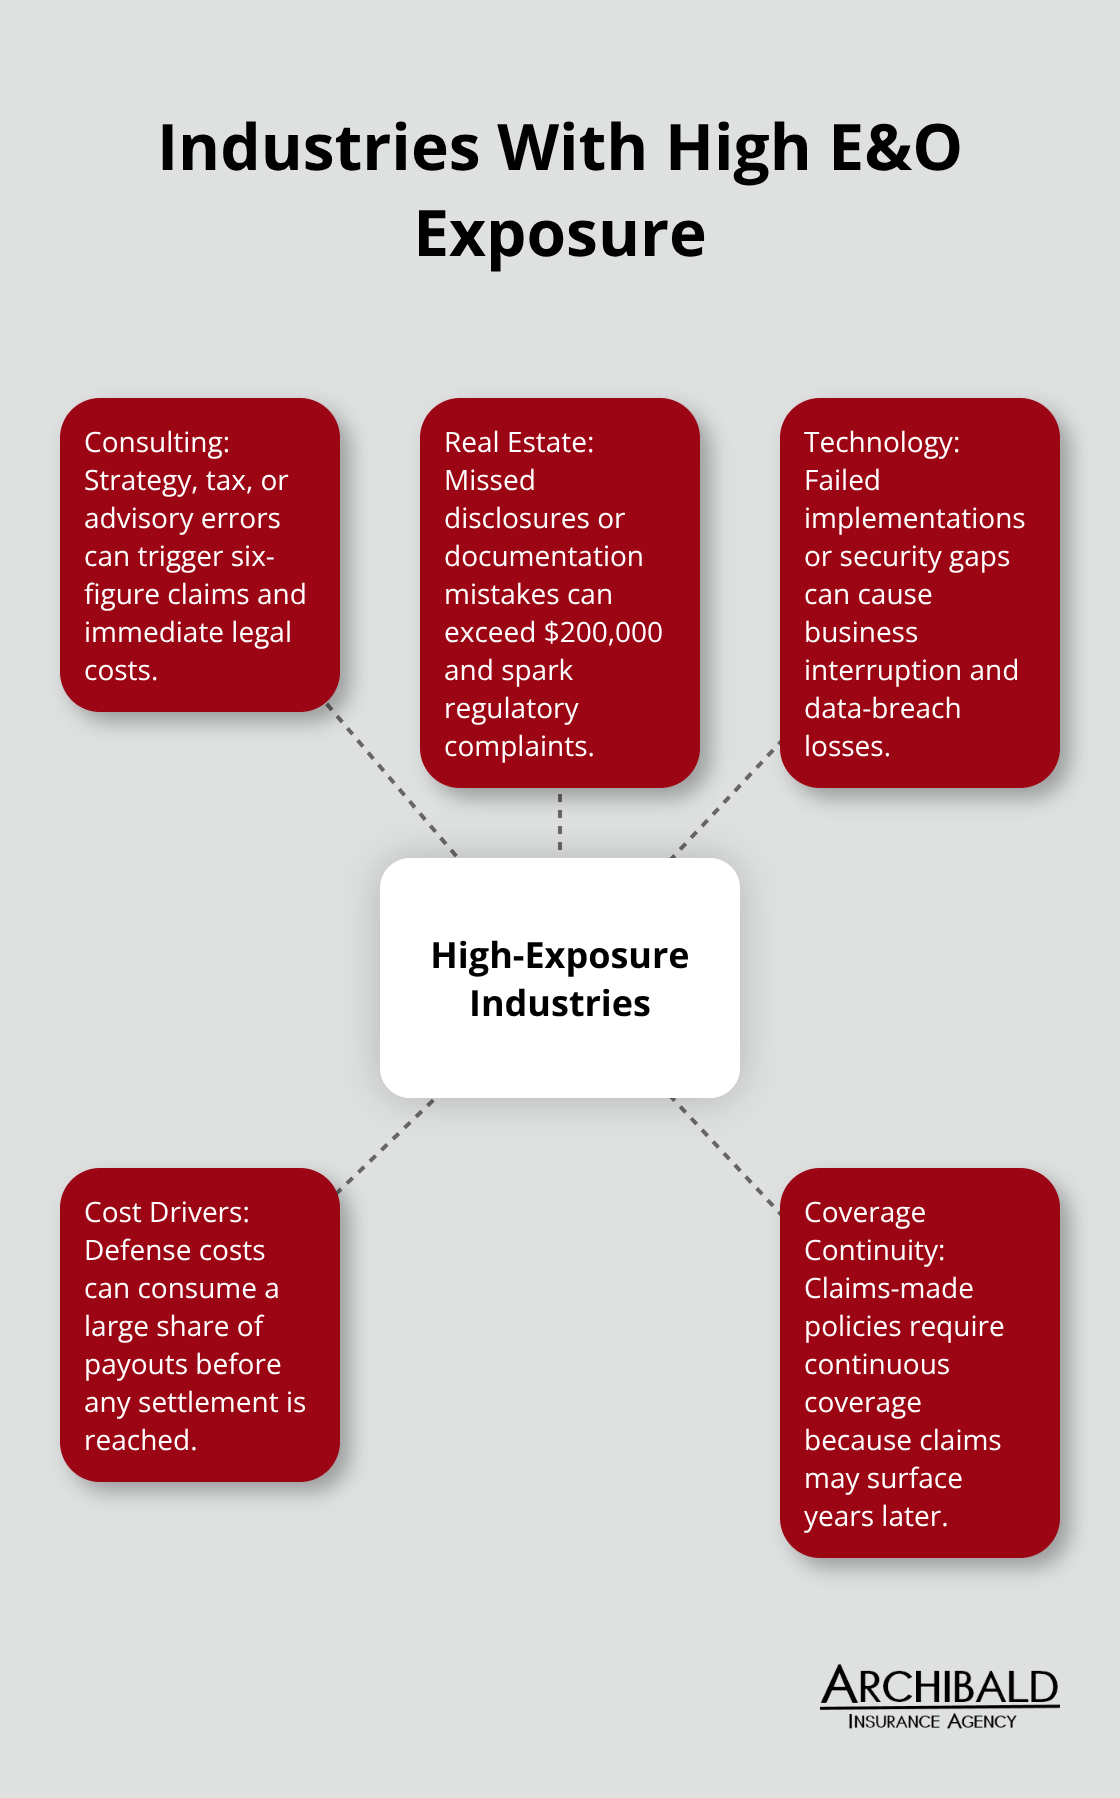
Consulting firms, real estate professionals, and technology companies operate in Utah’s competitive markets where a single mistake triggers expensive liability claims. These three industries face the highest frequency of E&O claims, and the numbers justify the urgency. Premium growth in the P&C industry slowed to a 4.6% increase in direct premiums written, with defense costs consuming 30-40% of total claim payouts before any settlement is reached.
Consultants and Advisors Face Immediate Financial Risk
Management consultants, tax advisors, and business strategists in Utah operate under intense pressure to deliver results. When your recommendations lead to poor decisions, clients sue without hesitation. A financial advisor who suggests an investment strategy that underperforms market benchmarks faces six-figure claims, especially if the client documents losses exceeding $500,000. Tax consultants who miss deductions or misinterpret regulations expose themselves to penalties plus client recovery actions. CPAs face professional liability exposure that requires adequate coverage to protect against claims.
Without E&O coverage, you remain personally liable for every dollar of damages and legal defense. Consultants operating as sole proprietors or small partnerships have zero buffer between a claim and personal bankruptcy. Your home, savings, and business assets become targets in settlement negotiations.
Real Estate Professionals Cannot Avoid Transaction Risks
Real estate agents and property managers in Utah handle transactions worth hundreds of thousands of dollars, creating enormous liability exposure. A missed disclosure about property defects, incorrect square footage documentation, or title issues generates claims exceeding $200,000. Property managers who fail to maintain rental properties adequately or mishandle tenant deposits face both civil lawsuits and regulatory complaints simultaneously. The Utah Division of Real Estate processes complaints regularly, and many lead to insurance claims.
Brokers increasingly require their agents to carry E&O coverage as a condition of employment, making this non-negotiable for anyone serious about the profession. Claims often arise years after the transaction closes, which is why continuous coverage matters more in real estate than in most industries. A gap in your policy leaves you exposed to claims that fall outside any protection period.
Technology and Software Companies Face Hidden Liability
Software developers and IT consultants in Utah create solutions that clients depend on for business operations. When your code fails, integrations break, or security vulnerabilities expose client data, the financial consequences extend far beyond the software itself. A failed software implementation costs a client millions in lost productivity and business interruption. Data breaches resulting from inadequate security measures generate claims that routinely exceed $500,000 when client notification costs and regulatory fines are included.
Tech companies often underestimate their E&O exposure because they focus on product liability rather than professional services liability. Your E&O policy covers the advice you gave, the specifications you missed, and the security standards you failed to implement. Without it, a single significant failure eliminates years of profits.
Understanding your industry’s specific risks helps you identify the coverage gaps that standard policies leave unprotected. Each sector requires different protection levels, which is why the next step involves selecting a policy that actually matches your business operations rather than settling for generic coverage.
How to Choose the Right E&O Policy
Document Your Actual Business Operations
Start with your real business operations, not a generic E&O policy template. You need to document your specific revenue sources, client types, and service delivery methods because these factors determine your actual exposure. A consultant who provides written reports faces different risk than one offering only verbal advice. A real estate agent handling commercial transactions needs higher limits than one focusing on residential sales. A software developer creating custom integrations needs broader coverage than one selling packaged solutions.
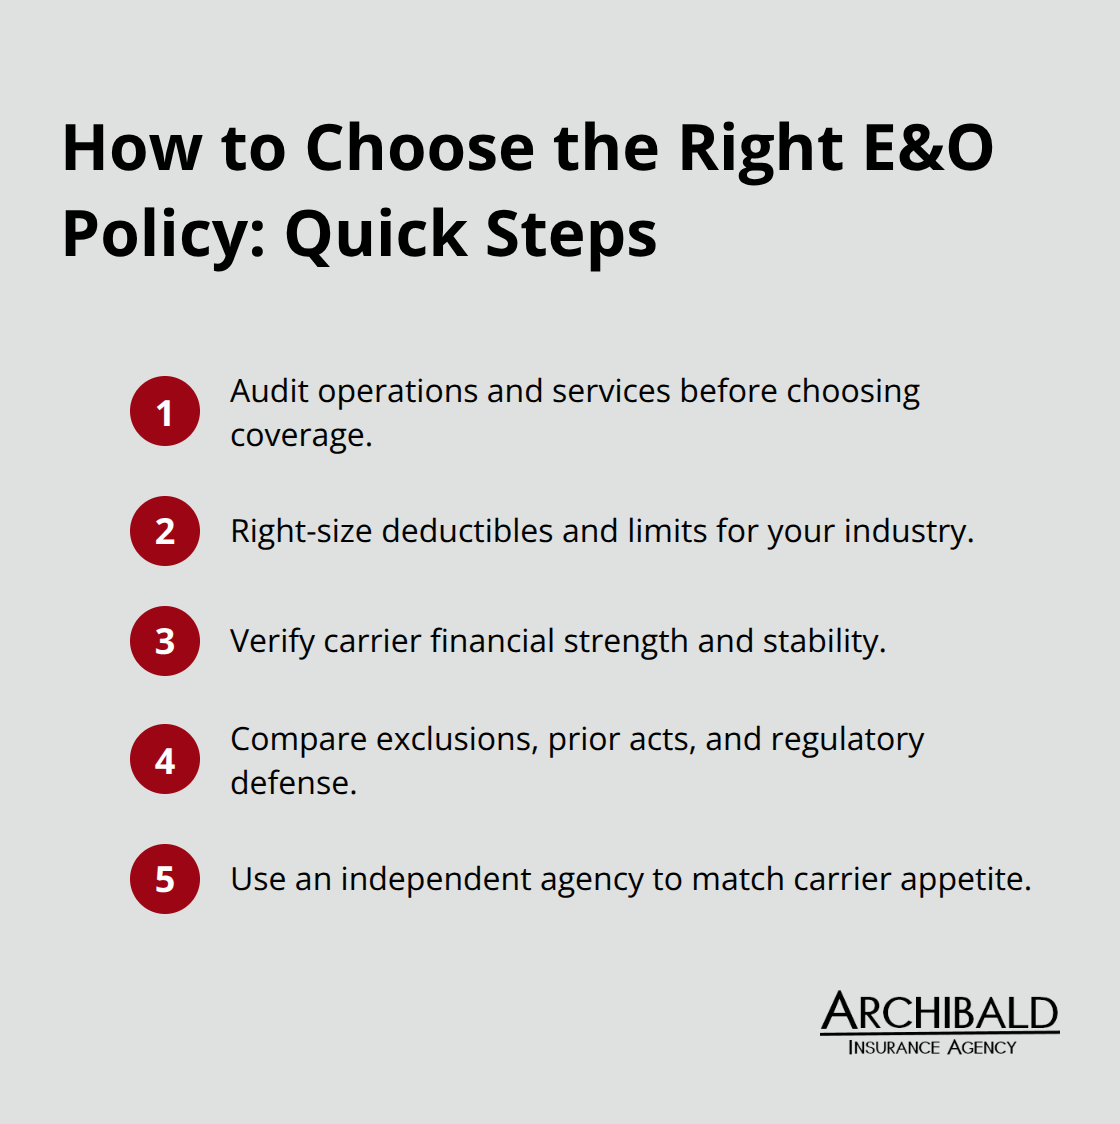
Choose a deductible you can actually afford to pay out of pocket, because a $10,000 deductible sounds manageable until your attorney bills $15,000 in the first month of defending a claim.
Set Coverage Limits Based on Your Industry
Coverage limits matter equally to deductible selection. Coverage limits for different professional industries vary significantly, ranging from $250,000 to $2 million and more depending on your field. Technology companies frequently require $2 million or higher because a single software failure can cascade into massive client losses.
Talk to other business owners in your exact field about their coverage limits. You’ll learn what claims actually look like in your industry rather than guessing based on worst-case scenarios. This peer intelligence proves far more valuable than theoretical risk assessments.
Evaluate Carrier Financial Strength and Stability
Carrier ratings and financial stability matter more than premium price because an insolvent insurer cannot pay your claim when you need it most. The National Association of Insurance Commissioners tracks insurer financial strength, and you should verify that any carrier you consider maintains an A.M. Best rating of A- or higher.
Utah has experienced rate increases across E&O lines, with some segments seeing premium growth annually according to industry reports. Locking in a stable carrier now protects you from future rate shocks.
Compare Quotes and Identify Coverage Gaps
Request three to five quotes from different carriers and compare not just premium but also what each policy excludes, because exclusions are where coverage actually dies. Some carriers exclude claims arising from prior acts or non-disclosed business operations, while others charge significantly higher premiums for those same exposures.
Ask specifically whether your policy covers regulatory defense costs if a client files a complaint with the Utah Division of Real Estate or other licensing boards, because that coverage often gets overlooked and results in thousands in unexpected legal bills. Verify whether your policy includes tail coverage options or requires you to purchase extended reporting period endorsements, because these add protection after you stop paying premiums or change carriers.
Work With an Agency That Represents Multiple Carriers
An independent agency that represents multiple carriers rather than one that pushes you toward their preferred partner will better serve your interests. Your specific risk profile may align better with one carrier’s underwriting appetite than another’s. An independent agency can match your actual exposure to the carrier that offers the best combination of price, coverage, and financial stability for your situation.
Final Thoughts
An E&O policy in Utah protects your business from the financial devastation that follows a professional mistake. Whether you consult on strategy, manage real estate transactions, or build custom software solutions, this coverage stands between your business and bankruptcy when liability claims arrive. The Council of Insurance Agents and Brokers reports that E&O claims increase 6% annually across professional services, and a single lawsuit costs $50,000 to $150,000 just to defend, even if you win.
Your next step involves identifying the specific coverage your industry requires, since consultants need different limits than real estate professionals and technology companies face exposures that generic policies miss entirely. Stop comparing E&O policies based on price alone-instead, compare what each policy actually covers, what it excludes, and whether the carrier can pay when you file a claim. Verify that regulatory defense costs are included (licensing board complaints generate legal bills that standard policies sometimes leave uncovered) and ask about tail coverage options before you need them.
Archibald Insurance Agency works with Utah business owners across consulting, real estate, technology, and other professional fields to find E&O coverage that matches your actual operations and budget. As an independent agency representing multiple carriers, we match your specific risk profile to the right policy rather than pushing you toward one carrier’s preferred solution. Contact us to discuss your E&O insurance needs and receive quotes that reflect your real business exposure.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation


