
Life Insurance Guide Utah: What Every Utah Family Should Know
Life insurance is one of the most important financial decisions Utah families make, yet many put it off or avoid it altogether. At Archibald Insurance Agency, we’ve helped hundreds of Utah families understand their options and protect what matters most.
This life insurance guide for Utah walks you through everything you need to know-from why coverage matters to which policy type fits your situation best.
Why Utah Families Need Life Insurance
The Immediate Financial Crisis Without Coverage
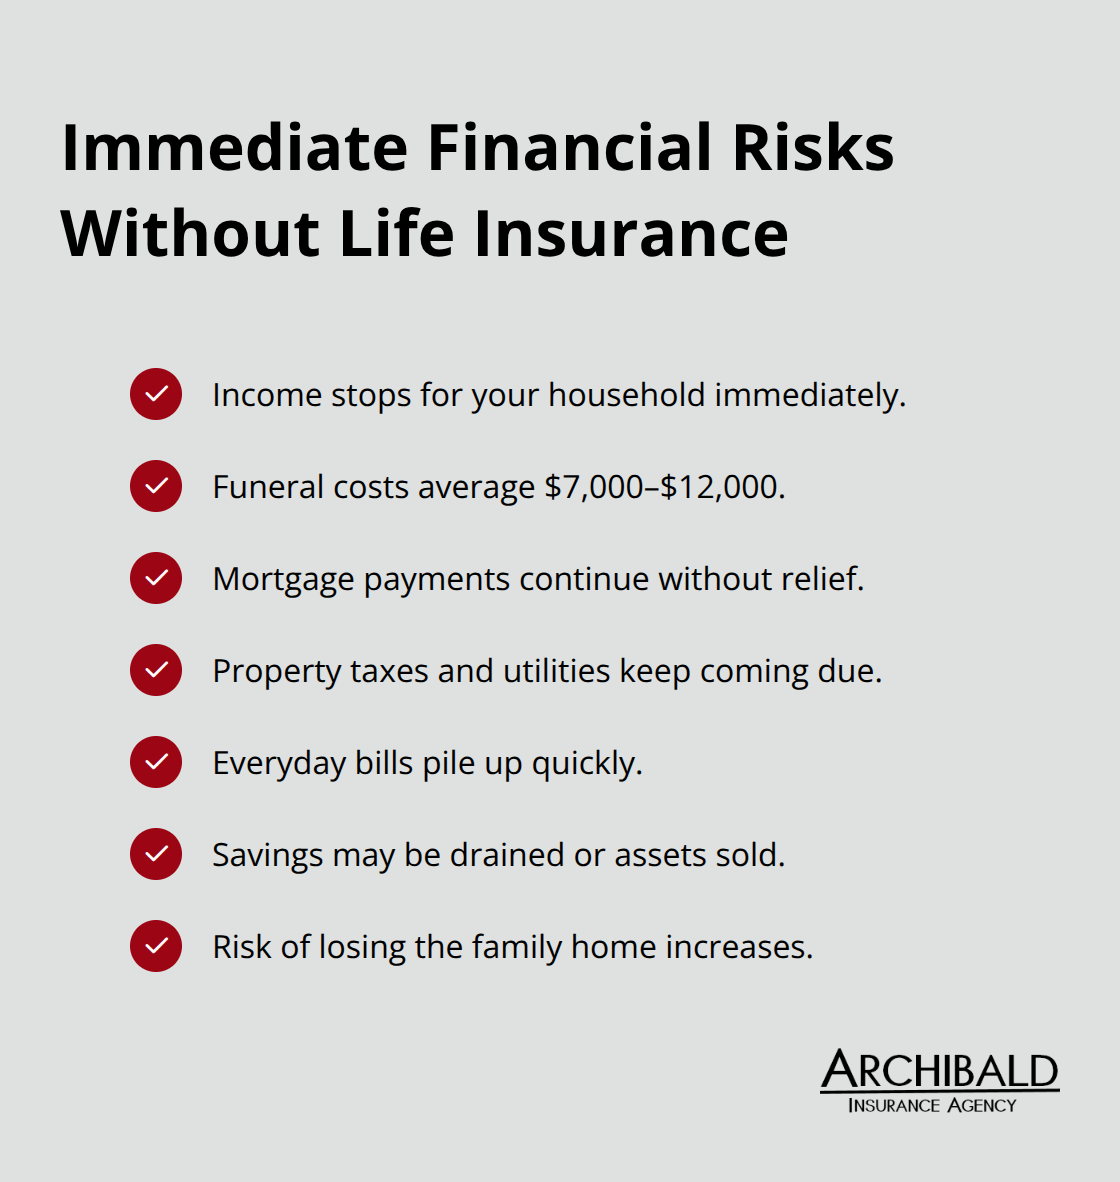
Without life insurance, your family faces immediate financial crisis if something happens to you. According to the U.S. Census Bureau, approximately 21 million Americans have no life insurance coverage whatsoever, and many Utah families fall into this risky category. The reality is stark: if you’re the primary earner and you pass away, your spouse and children lose your income instantly. Your family would need to cover your funeral costs, which average between $7,000 and $12,000 according to the National Funeral Directors Association.
Debts Don’t Disappear
Beyond that immediate expense, your mortgage doesn’t disappear, property taxes keep coming, and everyday bills continue piling up. Life insurance replaces your income and pays off these obligations so your family isn’t forced to sell the house, drain savings, or struggle through financial hardship during their most vulnerable time.
Utah’s Housing Market Makes Coverage Essential
Utah’s housing market makes this particularly relevant for local families. The median home price in Utah has climbed significantly in recent years, meaning most Utah homeowners carry substantial mortgages. If you die, your lender won’t forgive that debt-your family inherits it. Life insurance with a death benefit large enough to cover your mortgage balance protects your spouse from potentially losing the family home.
Income Replacement Protects Your Family’s Future
Life insurance covers car loans, credit card debt, and other obligations you’d leave behind. More importantly, it replaces your income so your children can stay in school, your spouse can manage household expenses, and your family maintains financial stability. Utah families with young children should view life insurance not as an optional luxury but as a fundamental financial responsibility that prevents generational financial damage.
Understanding why you need coverage is the first step. The next question becomes which type of policy actually fits your situation and budget.
Types of Life Insurance Available in Utah
Term Life Insurance: Affordability Meets Protection
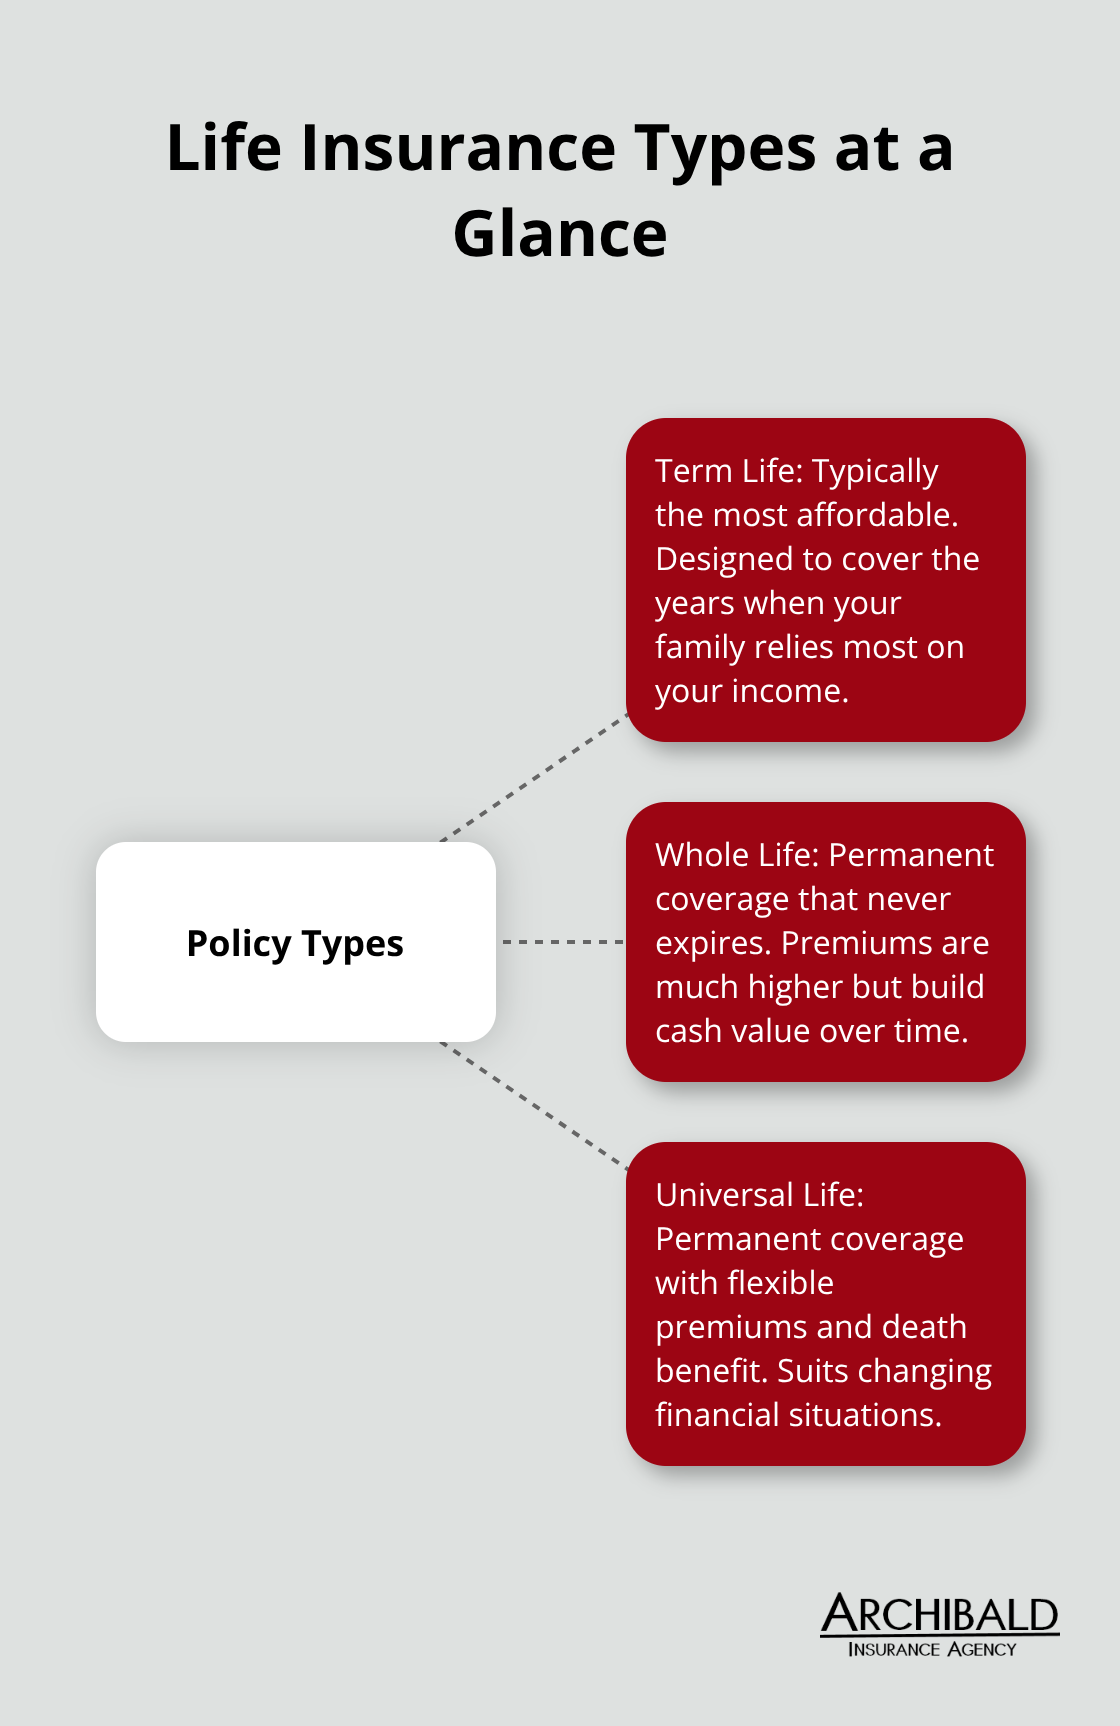
Term life insurance offers the most straightforward option for Utah families with dependents. A healthy 35-year-old can secure a $500,000 term policy for roughly $25 to $35 monthly. Your coverage expires after the term ends, but that actually works in your favor if your financial obligations shrink over time. Your mortgage decreases, your children become independent, and your retirement savings grow. Term insurance protects your family during the years when they depend most heavily on your income.
Most Utah families find that a 20 or 30-year term aligns perfectly with their mortgage timeline and their children’s ages.
Whole Life Insurance: Permanent Coverage at a Premium
Whole life insurance combines a death benefit with a cash value component that grows over your lifetime. This permanent coverage never expires, which appeals to families concerned about developing health conditions that might make future insurance unaffordable. However, whole life premiums run roughly 8 to 10 times higher than comparable term policies. A $500,000 whole life policy costs $200 to $300 monthly instead of $30. The higher cost reflects the lifetime protection and the cash value accumulation that builds within the policy.
Universal Life Insurance: Flexibility Between Extremes
Universal life insurance splits the difference by offering permanent coverage with lower premiums than whole life, though still substantially higher than term. The flexibility of universal policies lets you adjust your death benefit and premium payments throughout your life. This approach works well for business owners or high-net-worth individuals whose circumstances change dramatically. For most Utah families focused on protecting their children and paying off the mortgage, however, the affordability and simplicity of term insurance outweighs the permanence of whole life or the flexibility of universal coverage.
Matching Your Policy to Your Family’s Timeline
The goal isn’t to carry life insurance forever-it’s to protect your family during the years when losing your income would truly devastate them. Your coverage needs shift as your life progresses. Once your children finish school, your mortgage shrinks, and your retirement accounts grow, you may need less protection. Term insurance acknowledges this reality and prices accordingly. Whole life and universal policies ignore this timeline, charging you for permanent protection you may not actually need.
Understanding which policy type fits your situation requires looking at your specific numbers and obligations. Calculating exactly how much coverage your family actually needs comes next.
How to Choose the Right Life Insurance Policy
Calculate Your Actual Coverage Needs
The biggest mistake Utah families make is guessing at how much life insurance they actually need. You can’t pull a number from thin air and hope it works. Start with your mortgage balance-check your most recent statement or call your lender. If you owe $350,000 on your home, that’s the floor for your death benefit. Add your car loans, credit card balances, and any other debts. The National Foundation for Credit Counseling reports that the average American household carries roughly $145,000 in non-mortgage debt, though Utah families often carry less.
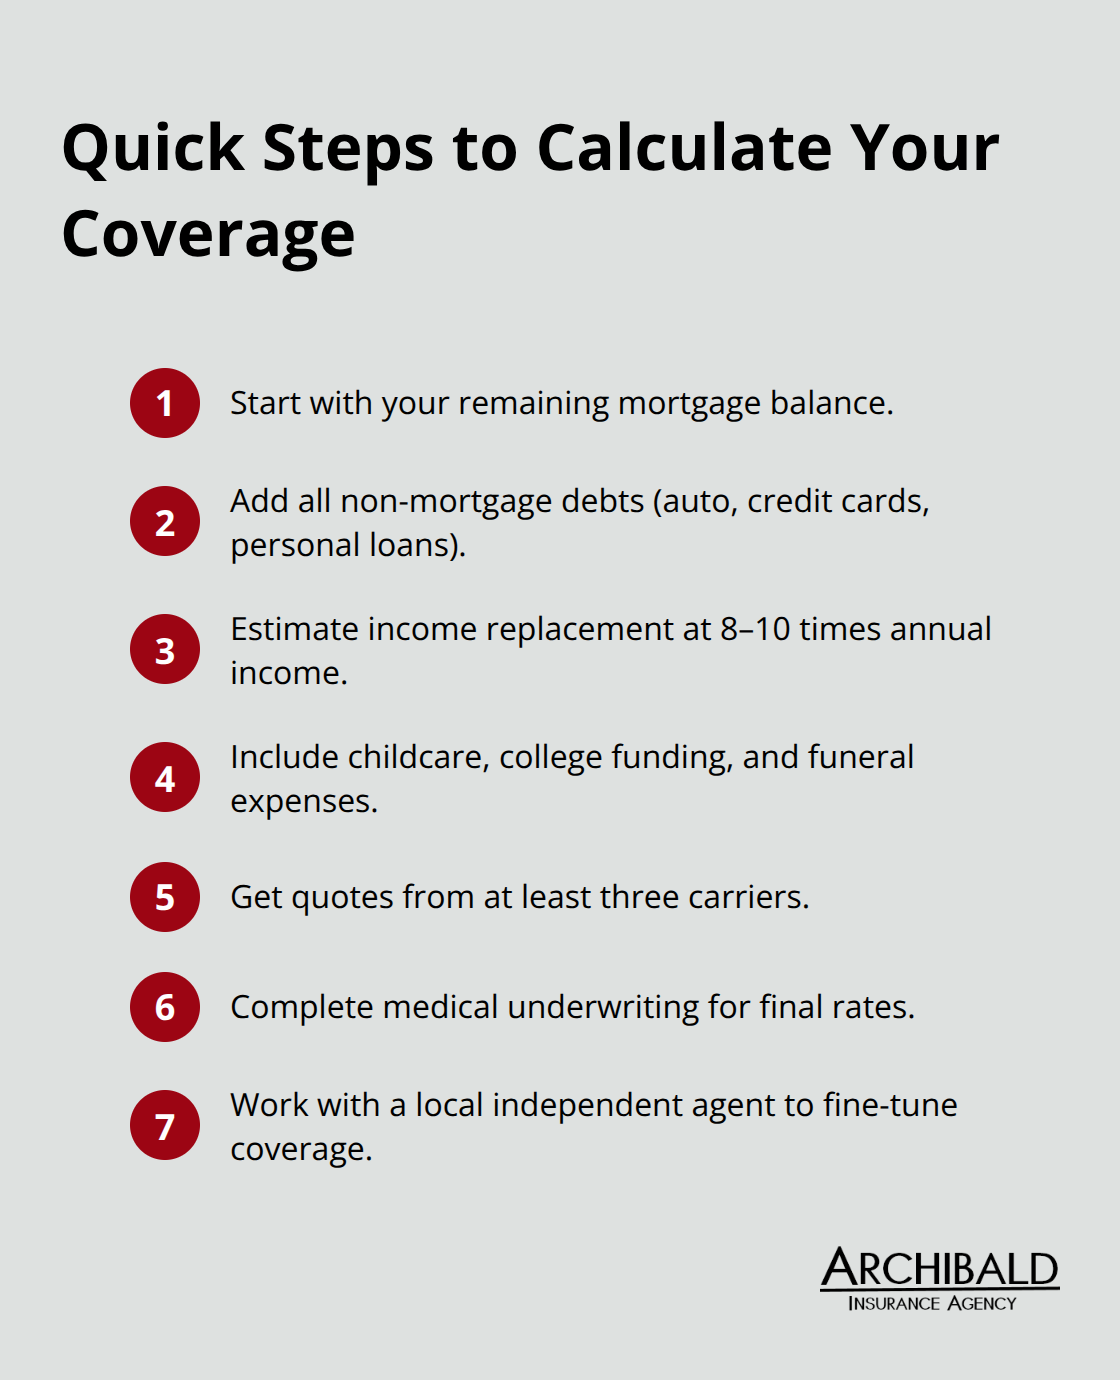
Next, calculate your actual coverage needs by multiplying your income by a variable based on factors such as age, occupation, and projected working years. If you earn $60,000 annually and your youngest child is 8 years old, you need approximately $660,000 just for income replacement through age 18. Most financial advisors recommend coverage of 8 to 10 times your annual income, which gives your family breathing room for unexpected expenses.
Account for Additional Expenses
Add childcare costs if your spouse would need to hire help, college funding if you want to cover education, and funeral expenses (which average between $7,000 and $12,000 according to the National Funeral Directors Association). The total will likely surprise you-and that’s why term insurance makes financial sense for most Utah families. A $750,000 death benefit costs far less than you expect.
Compare Quotes from Multiple Carriers
Once you know your target coverage amount, obtain quotes from at least three different carriers before making any decision. Premium prices vary dramatically between insurers for identical coverage, so comparing is non-negotiable. A 40-year-old non-smoker might pay $45 monthly with one carrier and $62 with another for the same $500,000 policy. Online quote tools give you ballpark figures instantly, but you’ll need medical underwriting for final approval.
Work with a Local Agent for Personalized Guidance
Work with a local agent who understands Utah’s specific market and your family’s situation rather than purchasing from a faceless online platform. Your agent should ask detailed questions about your health history, occupation, and financial obligations before recommending coverage amounts and policy types. As an independent agency, Archibald Insurance Agency represents multiple carriers, which means we find you the best rates available instead of pushing policies from a single company. This personalized approach prevents you from overpaying for coverage you don’t need or underinsuring your family.
Final Thoughts
Life insurance protects your family from financial devastation, and Utah families have concrete options that fit different budgets and timelines. Term life insurance offers affordable protection during your family’s most vulnerable years, while whole life and universal policies provide permanent coverage for those who want lifetime protection. The key is matching your policy type to your actual needs rather than overpaying for features you don’t require.
Your next step involves calculating exactly how much coverage your family needs by adding your mortgage balance, outstanding debts, income replacement requirements, and final expenses. Most Utah families find they need between $500,000 and $1,000,000 in coverage, which costs far less monthly than they expected. Once you know your target amount, obtain quotes from multiple carriers because premium prices vary significantly for identical coverage.
An independent agent represents multiple insurance companies, which means you get competitive rates instead of being locked into one carrier’s pricing. Contact Archibald Insurance Agency to discuss your life insurance guide Utah needs with someone who understands your community and can answer your specific questions about coverage amounts and policy types.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation


